A debt collector reports an unpaid account to the credit bureaus before you receive any written notice. Your score drops. You find out when a lender denies your application. According to the Fair Credit Reporting Act, collectors must follow specific accuracy and notice rules when reporting debts. If those rules were broken in your case, call +1-844-638-1122 for a free case review.
Key Takeaways
- Collectors must send a written validation notice within five days of first contact. Reporting to credit bureaus before that notice arrives may violate the FDCPA.
- Medical debts under $500 cannot be reported to credit bureaus. Medical debts cannot be reported until one year after first delinquency.
- A collection account can drop your credit score by 50 to 100 points. It can remain on your report for up to seven years from the date of first delinquency.
- Re-aging a debt is illegal under the FCRA. That means changing the delinquency date to make a debt look newer than it is.
- FCRA violations may entitle you to actual damages, up to $1,000 in statutory damages, and attorney fees.
- The Wood Firm PLLC handles FCRA and FDCPA cases on contingency. If the collector violated the law, they pay our fees.
Free Case Review: +1-844-638-1122
Can Debt Collectors Report You Without Notice
Yes. That is the gap federal law has not fully closed. Collectors must send a written validation notice within five days of first contact. But federal law does not require notice before first reporting to Equifax, Experian, or TransUnion.
This creates a specific harm: your credit score drops before you know a collector is pursuing the debt. You may never have received a letter, a call, or any contact. The first sign is a denied loan application or a rate increase on an existing account.
Some states have enacted pre-reporting notice requirements. Federal law has not. If a collector reported before sending your validation notice, that sequence may support an FDCPA claim. It may also support an FCRA claim simultaneously.
What the FDCPA Requires Before Credit Reporting
The FDCPA requires a written validation notice within five days of first contact. Collectors must send it before pursuing further collection. That notice must state the amount owed and the creditor’s name. It must also state your right to dispute within 30 days.
The notice does not explicitly reference credit reporting. If a collector reports before that notice reaches you, courts have found FDCPA claims can follow. The sequence itself is the problem. That dispute window exists to let you challenge the debt before it causes damage. The law created it for exactly this situation.
If you dispute in writing within 30 days, the collector must stop. It cannot resume until it provides written verification. Reporting an unverified debt to credit bureaus during that pause may be a separate violation. See why you should never ignore letters from collection agencies for guidance on your next step.
What the FCRA Requires From Collectors
The FCRA requires anyone reporting information to credit bureaus to follow reasonable procedures ensuring accuracy. Collectors must investigate disputes and correct inaccurate entries. They cannot report debts they know, or should know, are wrong.
Specific prohibitions under the FCRA include re-aging, duplicate reporting, and reinsertion of deleted information without new supporting evidence. Re-aging means changing the date of first delinquency to make a debt appear newer than it is. That practice extends the seven-year reporting window illegally.
When a collector sells a debt, the original agency must delete or mark its entry as transferred. Both agencies reporting the same debt as separate active collections may violate the FCRA’s accuracy requirements. In our practice, duplicate and re-aged entries are the most common FCRA violations in sold medical debt files. When we review an FCRA file, we pull the chain of ownership on every sold account. That is where re-aging most often occurs.
How a Collection Account Damages Your Credit
A new collection account can drop your credit score by 50 to 100 points. The impact is larger if your prior history was clean. Accounts with existing negative marks see smaller drops.
The account stays on your report for up to seven years from the original date of first delinquency. That clock does not restart when a debt is sold to a new collector. It does not restart when you make a payment either.
A lower score triggers consequences beyond denied credit applications. Interest rates rise on variable-rate accounts. Insurance premiums increase. Landlords reject rental applications. Some employers screen credit reports for finance, government, and security-clearance positions. For more on medical debt reporting, see how medical debt collectors cross the line and what’s illegal.
Medical Debt Reporting Rules
Medical debt carries its own reporting restrictions. As of 2023, medical debts under $500 cannot appear on credit reports at all. Medical debts cannot be reported until one year after first delinquency, giving consumers time to resolve insurance disputes.
Newer scoring models (FICO 9 and VantageScore 3.0) ignore paid medical collections. But many lenders still use older models that treat all collections equally. A paid medical collection may still harm your application under those models.
If a collector reported a medical debt under $500, the entry may be removable. The same applies if reporting happened before the one-year window closed. A federal claim may exist regardless of whether the underlying balance is accurate.
What Collectors Cannot Legally Report
Federal law prohibits specific reporting practices. Knowing them helps you identify violations in your own credit file.
- Inaccurate amounts: collectors cannot report wrong balances or fees not authorized by the original agreement. Amounts inflated after charge-off are also prohibited.
- Re-aging: changing the delinquency date to extend the seven-year window is illegal under the FCRA.
- Duplicate reporting: multiple agencies cannot each list the same debt as a separate active collection after a sale.
- Unverified debt: reporting a disputed debt before providing verification may violate accuracy requirements.
- Paid debts marked unpaid: once you submit proof of payment, continued reporting of the balance as unpaid may violate the FCRA.
- Re-insertion without notice: after a bureau deletes an entry, the collector cannot re-report it. New evidence and bureau notification are both required.
- Debts past seven years: collectors cannot report accounts beyond seven years from the original date of first delinquency.
How to Dispute a Collection on Your Credit Report
Send written disputes to the credit bureau and directly to the collector. Use certified mail with return receipt requested. Keep copies of everything you send and every response you receive.
The bureau must investigate within 30 days. It contacts the collector, reviews the evidence, and either verifies or deletes the entry. If the collector cannot verify the debt, the bureau must delete it. During the investigation, the entry appears as “in dispute” on your report.
If the bureau verifies the entry as accurate, you may still add a 100-word statement to your file. That statement appears whenever the report is pulled. That statement appears whenever the report is pulled. It is not a substitute for legal action, but it creates a record. Before filing a dispute, see how to document debt collection harassment the right way for a step-by-step approach.
Your Rights Under the FCRA
The FCRA gives you specific, enforceable rights against inaccurate reporting. These rights exist whether or not the underlying debt is valid.
- Right to accurate information: bureaus and collectors must follow reasonable procedures to ensure accuracy. Reporting information they know is wrong violates the FCRA.
- Right to dispute: you can challenge any inaccurate entry. Bureaus must investigate within 30 days and verify or delete.
- Right to a statement: if a dispute is rejected, you may add a 100-word explanation to your file.
- Right to adverse action notice: credit, housing, or job denials based on your report require written notice. That notice must identify the bureau that supplied it.
- Right to additional free reports: adverse action, job loss, or identity theft each entitle you to extra free copies beyond the annual report.
- Right to sue: FCRA violations entitle you to actual damages and up to $1,000 per willful violation. Attorney fees are recoverable if you prevail.
In our experience, consumers who discover FCRA violations have often tried to resolve them alone first. Bureau investigations frequently side with the reporting collector. When that happens, an attorney’s review of the original account documents often reveals the error bureaus missed.
How The Wood Firm PLLC Handles FCRA and FDCPA Credit Reporting Cases
The Wood Firm PLLC reviews credit reporting cases for violations with the clearest legal consequences. Those are: debts reported before validation notices were sent, re-aged entries, and duplicate listings of sold accounts. Medical debts reported in violation of post-2023 rules also apply. The firm works entirely on contingency. If the collector or bureau violated federal law, they pay our fees separately from any damages you recover.
The firm represents consumers only and has never represented a creditor or collector. When you call, a team member reviews your credit reports and documents the specific entries at issue. The firm handles all contact with collectors and bureaus from that point forward. Reach us at +1-844-638-1122.
Did a collection appear on your report without prior notice? Visit our contact page or call +1-844-638-1122 for a free case review. The Wood Firm PLLC handles these cases on contingency: if the law was violated, they pay our fees.
Frequently Asked Questions
Can debt collectors report me to credit bureaus without warning
Yes. Federal law does not require collectors to notify you before first reporting a debt. But collectors must send a written validation notice within five days of first contact. If reporting preceded that notice, that sequence may support an FDCPA claim.
How long does a collection account stay on my credit report
A collection account stays on your report for up to seven years from the original delinquency date. That clock does not restart when the debt is sold or when you make a payment.
What should I do if I find a collection I never knew about
Dispute the entry in writing with the bureau and the collector immediately. Check whether you ever received a validation notice. An attorney can assess whether the lack of prior notice supports a federal claim.
Can collectors report the same debt multiple times
No. When a debt is sold, the previous collector must delete or mark its entry as transferred. Multiple active listings of the same debt may violate the FCRA’s accuracy requirements.
Will disputing a collection hurt my credit score
No. Disputing does not lower your score. During the investigation, the entry is marked “in dispute.” Some scoring models weight disputed items less. Your score may improve slightly during that period.
What if I paid the debt but it still shows as unpaid
Dispute the entry directly with both the bureau and the collector, and include proof of payment. Continuing to report a paid debt as unpaid after receiving that proof may violate the FCRA.
Can I sue a collector for damaging my credit with false information
Yes. If a collector reported information it knew was inaccurate, you may have an FCRA claim. Prevailing plaintiffs recover actual damages, up to $1,000 in statutory damages per willful violation, and attorney fees.
What is re-aging and why does it matter
Re-aging means changing the date of first delinquency to make a debt appear newer than it is. This practice extends the seven-year reporting window illegally and is a violation of the FCRA.
How long do I have to sue over a credit reporting violation
The FCRA generally allows two years from discovery of the violation, with a five-year outer limit. Consult an attorney promptly. Evidence is easier to preserve early, and the clock runs from when you discovered the problem.
Take Action Before the Reporting Does More Damage
Every month an inaccurate entry stays on your report, it affects credit applications and interest rates. Some losses, like denied loans and higher rates, you may never trace back to it. Pull your reports now, document what you find, and call +1-844-638-1122 if any entry looks wrong. The Wood Firm PLLC reviews these cases at no upfront cost. If the collector or bureau broke the law, they pay.
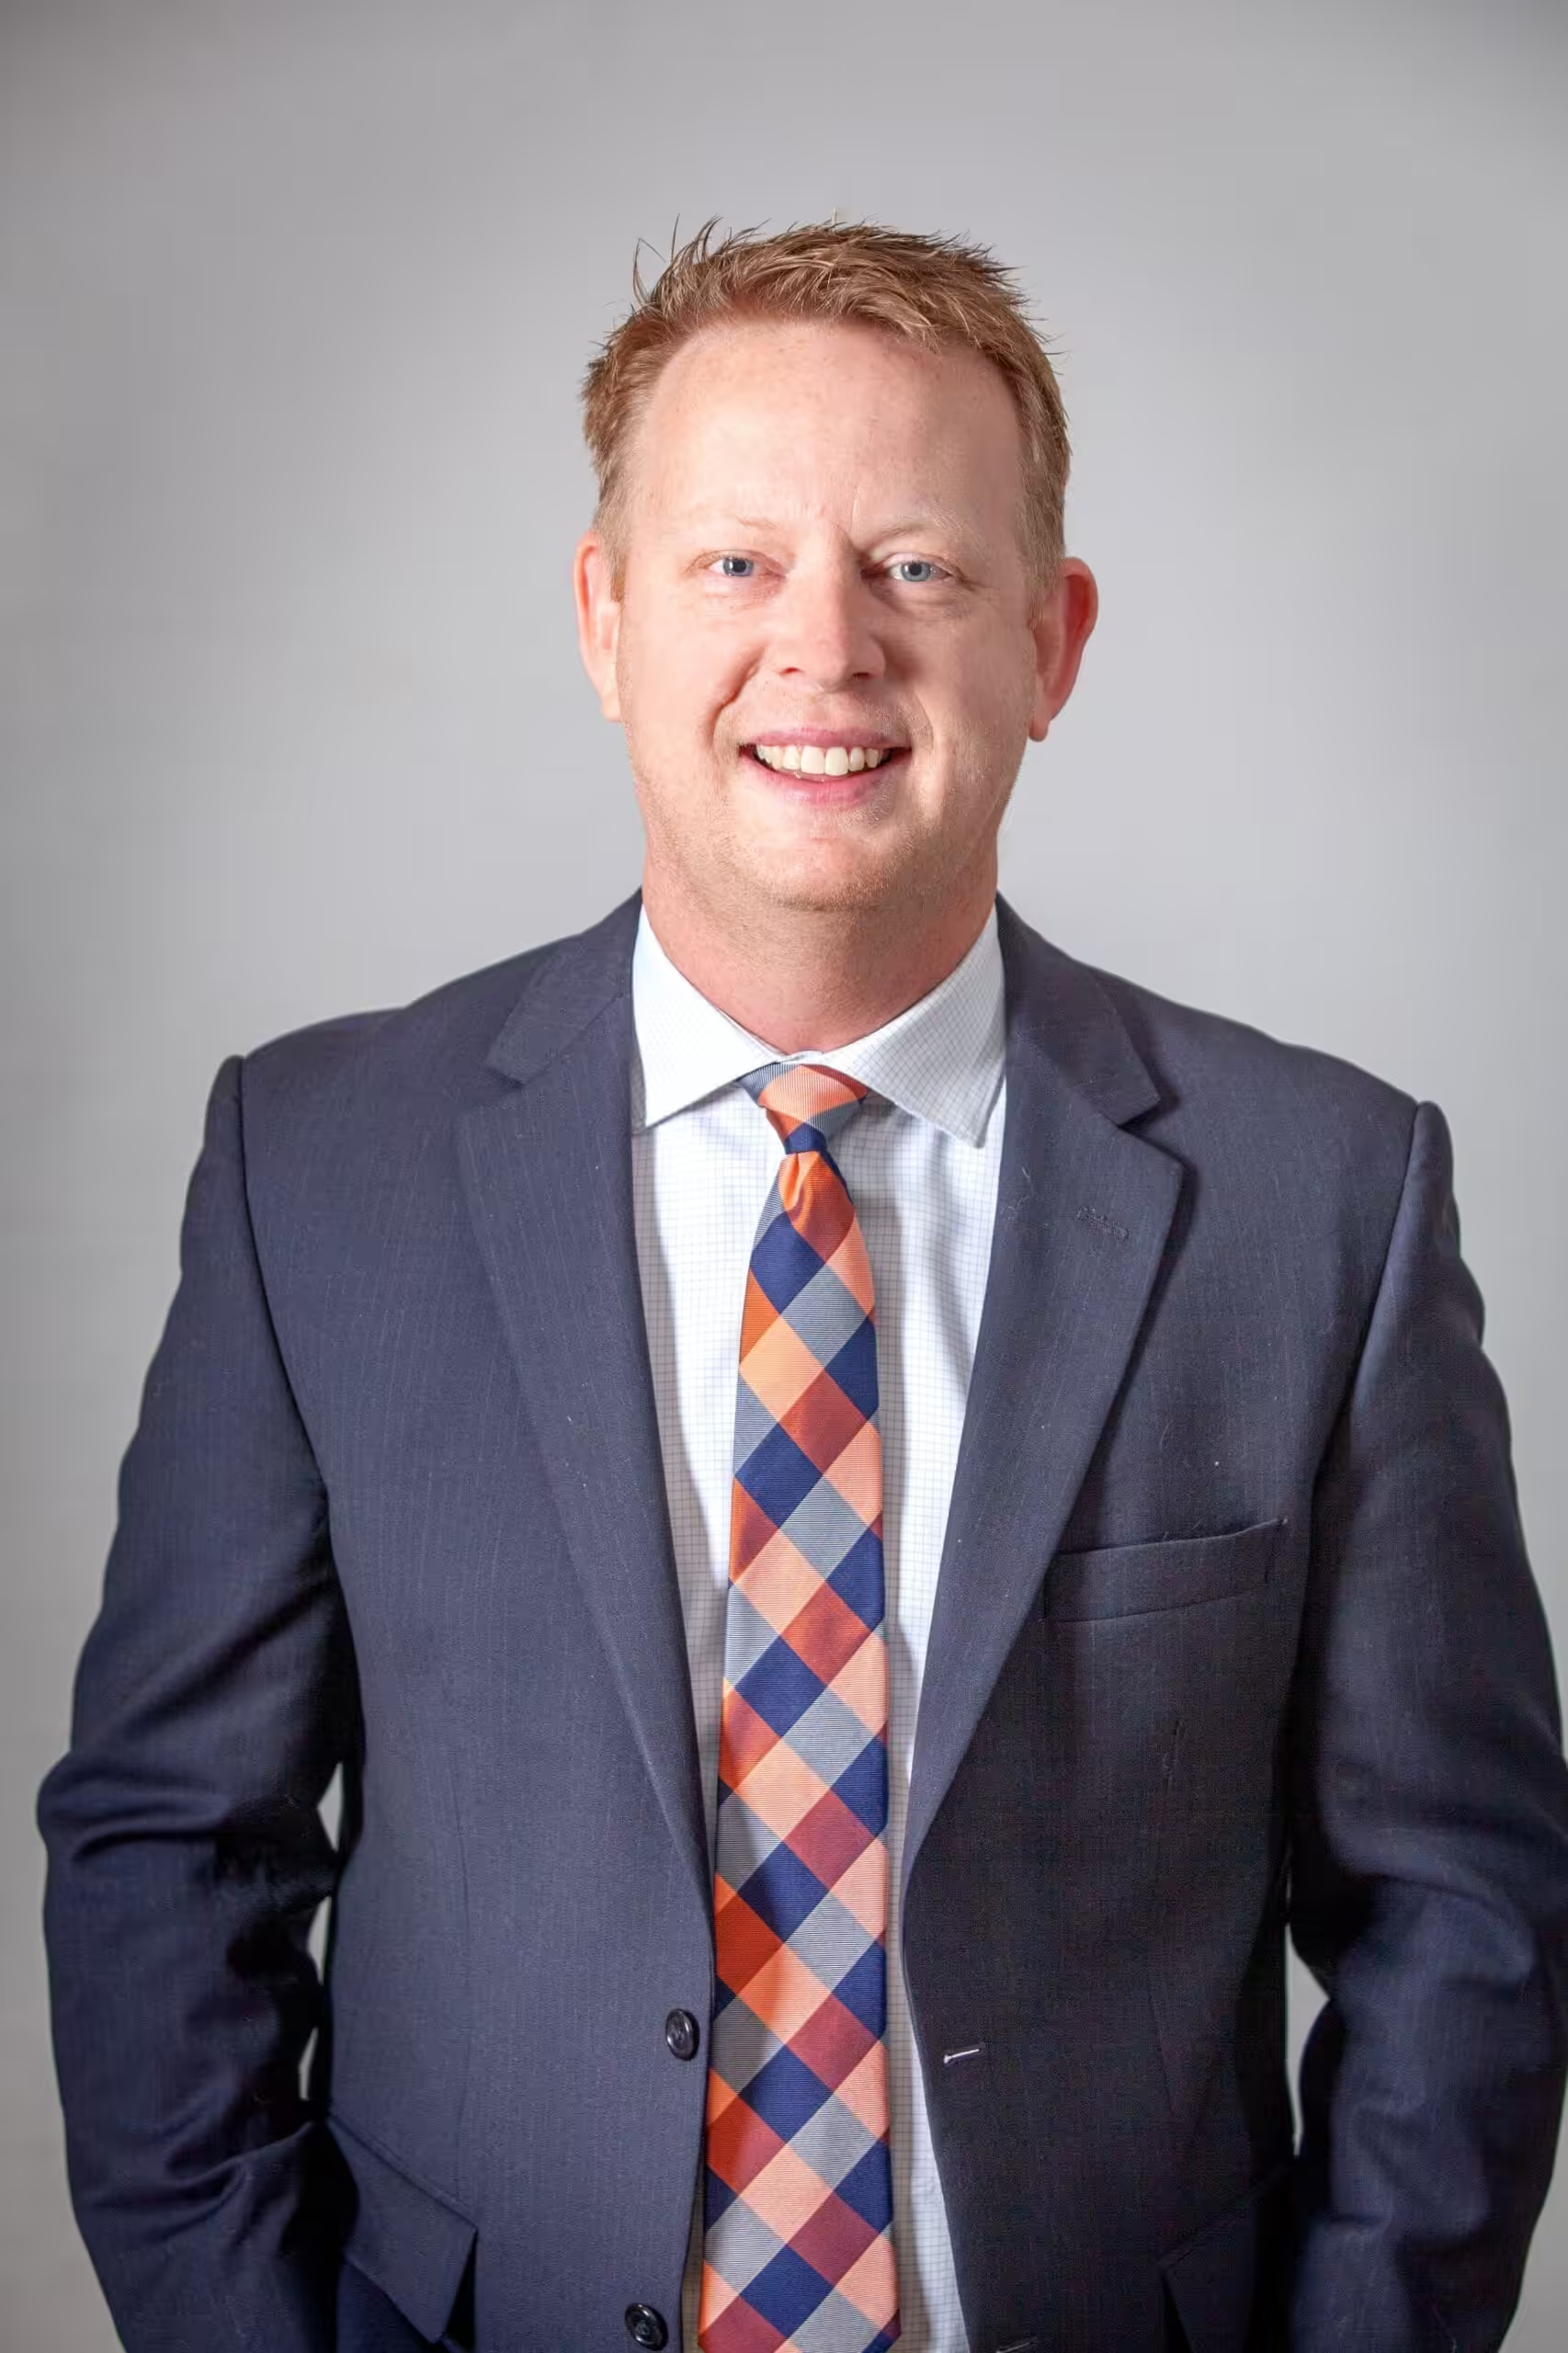
Jeff Wood represents consumers exclusively — never creditors or collectors. He holds federal court admissions across 9 districts, including all courts of AR, CO, NM, and TX. He practices from Little Rock, AR.