Creditors Protection Service, operating as Credit Protection Association, markets itself as a credit management service. Member businesses pay an annual subscription that covers credit reporting, risk assessment, and overdue account recovery. That subscription model does not exempt the company from federal law, regardless of its marketing.
Key Takeaways
- Creditors Protection Service (CPS), operating as Credit Protection Association (CPA), has been based in Rockford, Illinois, since 1963.
- CPA sells member businesses an annual subscription covering credit reporting, risk assessment, and debt recovery, rather than working on straight contingency.
- In Gruber v. Creditors’ Protection Service, the Seventh Circuit reviewed CPA’s collection letters under the FDCPA’s “unsophisticated consumer” standard.
- Consumer accounts describe tactics common to traditional collectors, including frequent calls and workplace contact, according to complaint patterns.
- If CPA violated the FDCPA, consumers may recover up to $1,000 in statutory damages, plus attorney fees.
- The Wood Firm PLLC reviews CPA cases on contingency, so you pay nothing unless we recover damages.
Free Case Review: +1-844-638-1122
Who Is Creditors Protection Service?
Creditors Protection Service, operating as Credit Protection Association, is a credit management service based in Rockford, Illinois. The company has operated since 1963. Unlike a typical debt collection agency, CPA positions itself as an all-in-one service for member businesses.
Its membership model includes credit reporting, risk assessment, credit limit recommendations, and overdue account recovery. That subscription structure differs from agencies that work on a straight contingency percentage of what they recover.
In our practice, we treat CPA’s subscription model as separate from whether any individual call breaks federal law. Members pay CPA regardless of outcome. Its tactics still must meet the same FDCPA and TCPA standards as any other collector.
How Can You Contact Creditors Protection Service?
You can contact Creditors Protection Service using the address and phone numbers on file below. Send any written correspondence, including validation and cease and desist letters, to the address listed here.
- Also Known As: Credit Protection Association, CPA, CPS
- Address: 308 W. State St., Suite 485, Rockford, IL 61101
- Phone: 815-964-9331 | (815) 964-9331 | +1-815-964-9331 | 8159649331
- Secondary Phone: 800-964-3087 | (800) 964-3087 | +1-800-964-3087 | 8009643087
Why Is Creditors Protection Service Calling You?
Creditors Protection Service is calling you because a member business referred your overdue account for recovery. CPA’s model moves through stages, starting with standard collection calls and letters. If those attempts fail, the company may escalate to more aggressive recovery tactics or legal action.
Because CPA serves paying members rather than working on contingency, some consumers report disproportionate pressure. If you notice repeated calls, workplace contact, or escalating threats, document each one as it happens.
What Does CPA’s Escalation Model Look Like?
Credit Protection Association describes a tiered approach to unpaid accounts. Standard recovery calls and letters come first. If those attempts fail, CPA may move to more intense recovery services, then legal referral.
Consumers report that the tone and frequency of contact can shift noticeably at each stage.
A subscription model can create pressure to show member businesses that the service delivers results. That pressure does not change what federal law allows CPA to say or how often it can call. CPA collects for member creditors rather than purchasing your debt outright.
What Other Collectors Use Similar Tactics?
The Wood Firm PLLC has helped consumers stop similar tactics from agencies like FBCS and First Credit Services. Both use professional or technology-driven positioning that can mask aggressive collection practices. The same FDCPA and TCPA protections apply no matter how a collector markets itself.
Is Creditors Protection Service a Scam?
Creditors Protection Service is a real, licensed credit management company, not an impersonator. It has operated since 1963 under the Credit Protection Association name. Licensed status and decades in business do not mean every tactic it uses is legal.
Consumer accounts describe excessive phone calls and workplace contact after being asked to stop. A representative who threatens legal action without authority to file may be violating the FDCPA.
In our practice, we compare what a CPA representative said against what the company can actually document. A subscription-based collector still has to prove the debt, the amount, and its authority to collect.
Is Creditors Protection Service Banned by the FTC?
No. Creditors Protection Service has not been banned by the FTC, based on available public records. That absence does not mean its conduct has escaped scrutiny.
Consumers can file complaints with the CFPB and the Illinois Attorney General. Both agencies can investigate patterns across many complaints even without an outright FTC ban.
What Did the Gruber Case Establish About CPA’s Letters?
Gruber v. Creditors’ Protection Service, Inc., 742 F.3d 271 (7th Cir. 2014), is the most cited federal case involving the company. The Seventh Circuit reviewed CPA’s collection letters under the FDCPA’s “unsophisticated consumer” standard.
The court sided with CPA on the letters at issue. It found the verification-request language satisfied FDCPA notice requirements. The court also found the phrase about wanting to pay a just debt was non-actionable puffery, not misleading.
The case still matters: it confirms courts judge CPA’s letters by how an unsophisticated consumer reads them. When we review a CPA letter, we apply that same standard to its specific language.
How The Wood Firm PLLC Helps Stop Creditors Protection Service Harassment
The Wood Firm PLLC reviews your calls and correspondence with Creditors Protection Service for FDCPA and TCPA violations. We look at call frequency, workplace contact, validation requests, and any threats of legal action CPA cannot support.
We work on contingency, so you pay nothing upfront. If CPA violated federal law, they pay our fees. Call The Wood Firm PLLC today at +1-844-638-1122.
Dealing with Creditors Protection Service does not mean you have no options. Visit our contact page or call +1-844-638-1122 for a free case review. The Wood Firm PLLC works on contingency, and CPA pays our fees if it broke federal law.
Is Creditors Protection Service a Legitimate Company?
Yes, Creditors Protection Service, also called Credit Protection Association, is a legitimate company operating since 1963. Its integrated business model does not exempt it from the FDCPA or TCPA.
What Is Credit Protection Association’s Integrated Model?
CPA sells member businesses an annual subscription covering credit reporting, risk assessment, and overdue account recovery. This differs from traditional collectors that work on a contingency percentage of what they recover.
Can Creditors Protection Service Threaten Legal Action Against You?
Only if the company actually intends to file suit and has the authority to do so. An empty threat made during a collection call may violate the FDCPA. Ask for written confirmation of any claimed legal action before you respond.
Can Creditors Protection Service Contact Your Employer?
Only once, and only to verify your employment for location purposes. They cannot discuss your debt with your employer or call your workplace repeatedly. See our guide on whether a collection agency can call your job for more detail.
Can Creditors Protection Service Threaten to Garnish Your Wages?
Not without first suing you and winning a court judgment. A threat to garnish wages before a judgment exists may violate the FDCPA. See our guide on whether a collection agency can threaten to garnish your wages.
How Do You Dispute a Debt Creditors Protection Service Says You Owe?
Send a written validation request by certified mail within 30 days of the first contact. Ask for the original creditor’s name, the amount owed, and proof CPA is authorized to collect. If CPA continues collection without providing that proof, it may be violating the FDCPA.
Can You Negotiate a Settlement With Creditors Protection Service?
Yes, CPA may accept a lump-sum settlement for less than the full balance, especially on older accounts. Get any settlement offer in writing before you pay anything. A written agreement protects you if a dispute arises later about what was actually promised.
What Should You Document If Creditors Protection Service Contacts You?
Keep a detailed log with the date, time, caller name, and a summary of each call. Note which stage the representative describes: standard recovery, more intense recovery, or legal referral. Save voicemails and any written correspondence.
In our practice, that stage-by-stage log often shows a pattern no single call reveals alone. A documented pattern also strengthens a claim if CPA continued contact after a cease and desist letter.
What Should You Do Next About Creditors Protection Service?
Deciding your next step starts with reviewing your call log and any letters from Creditors Protection Service. If you spot a possible FDCPA or TCPA violation, act before deadlines pass. Federal law gives you only a limited window to file a claim, so early documentation matters most.
The Wood Firm PLLC offers a free, no-obligation case review on contingency. Call us today at +1-844-638-1122 to find out where you stand.
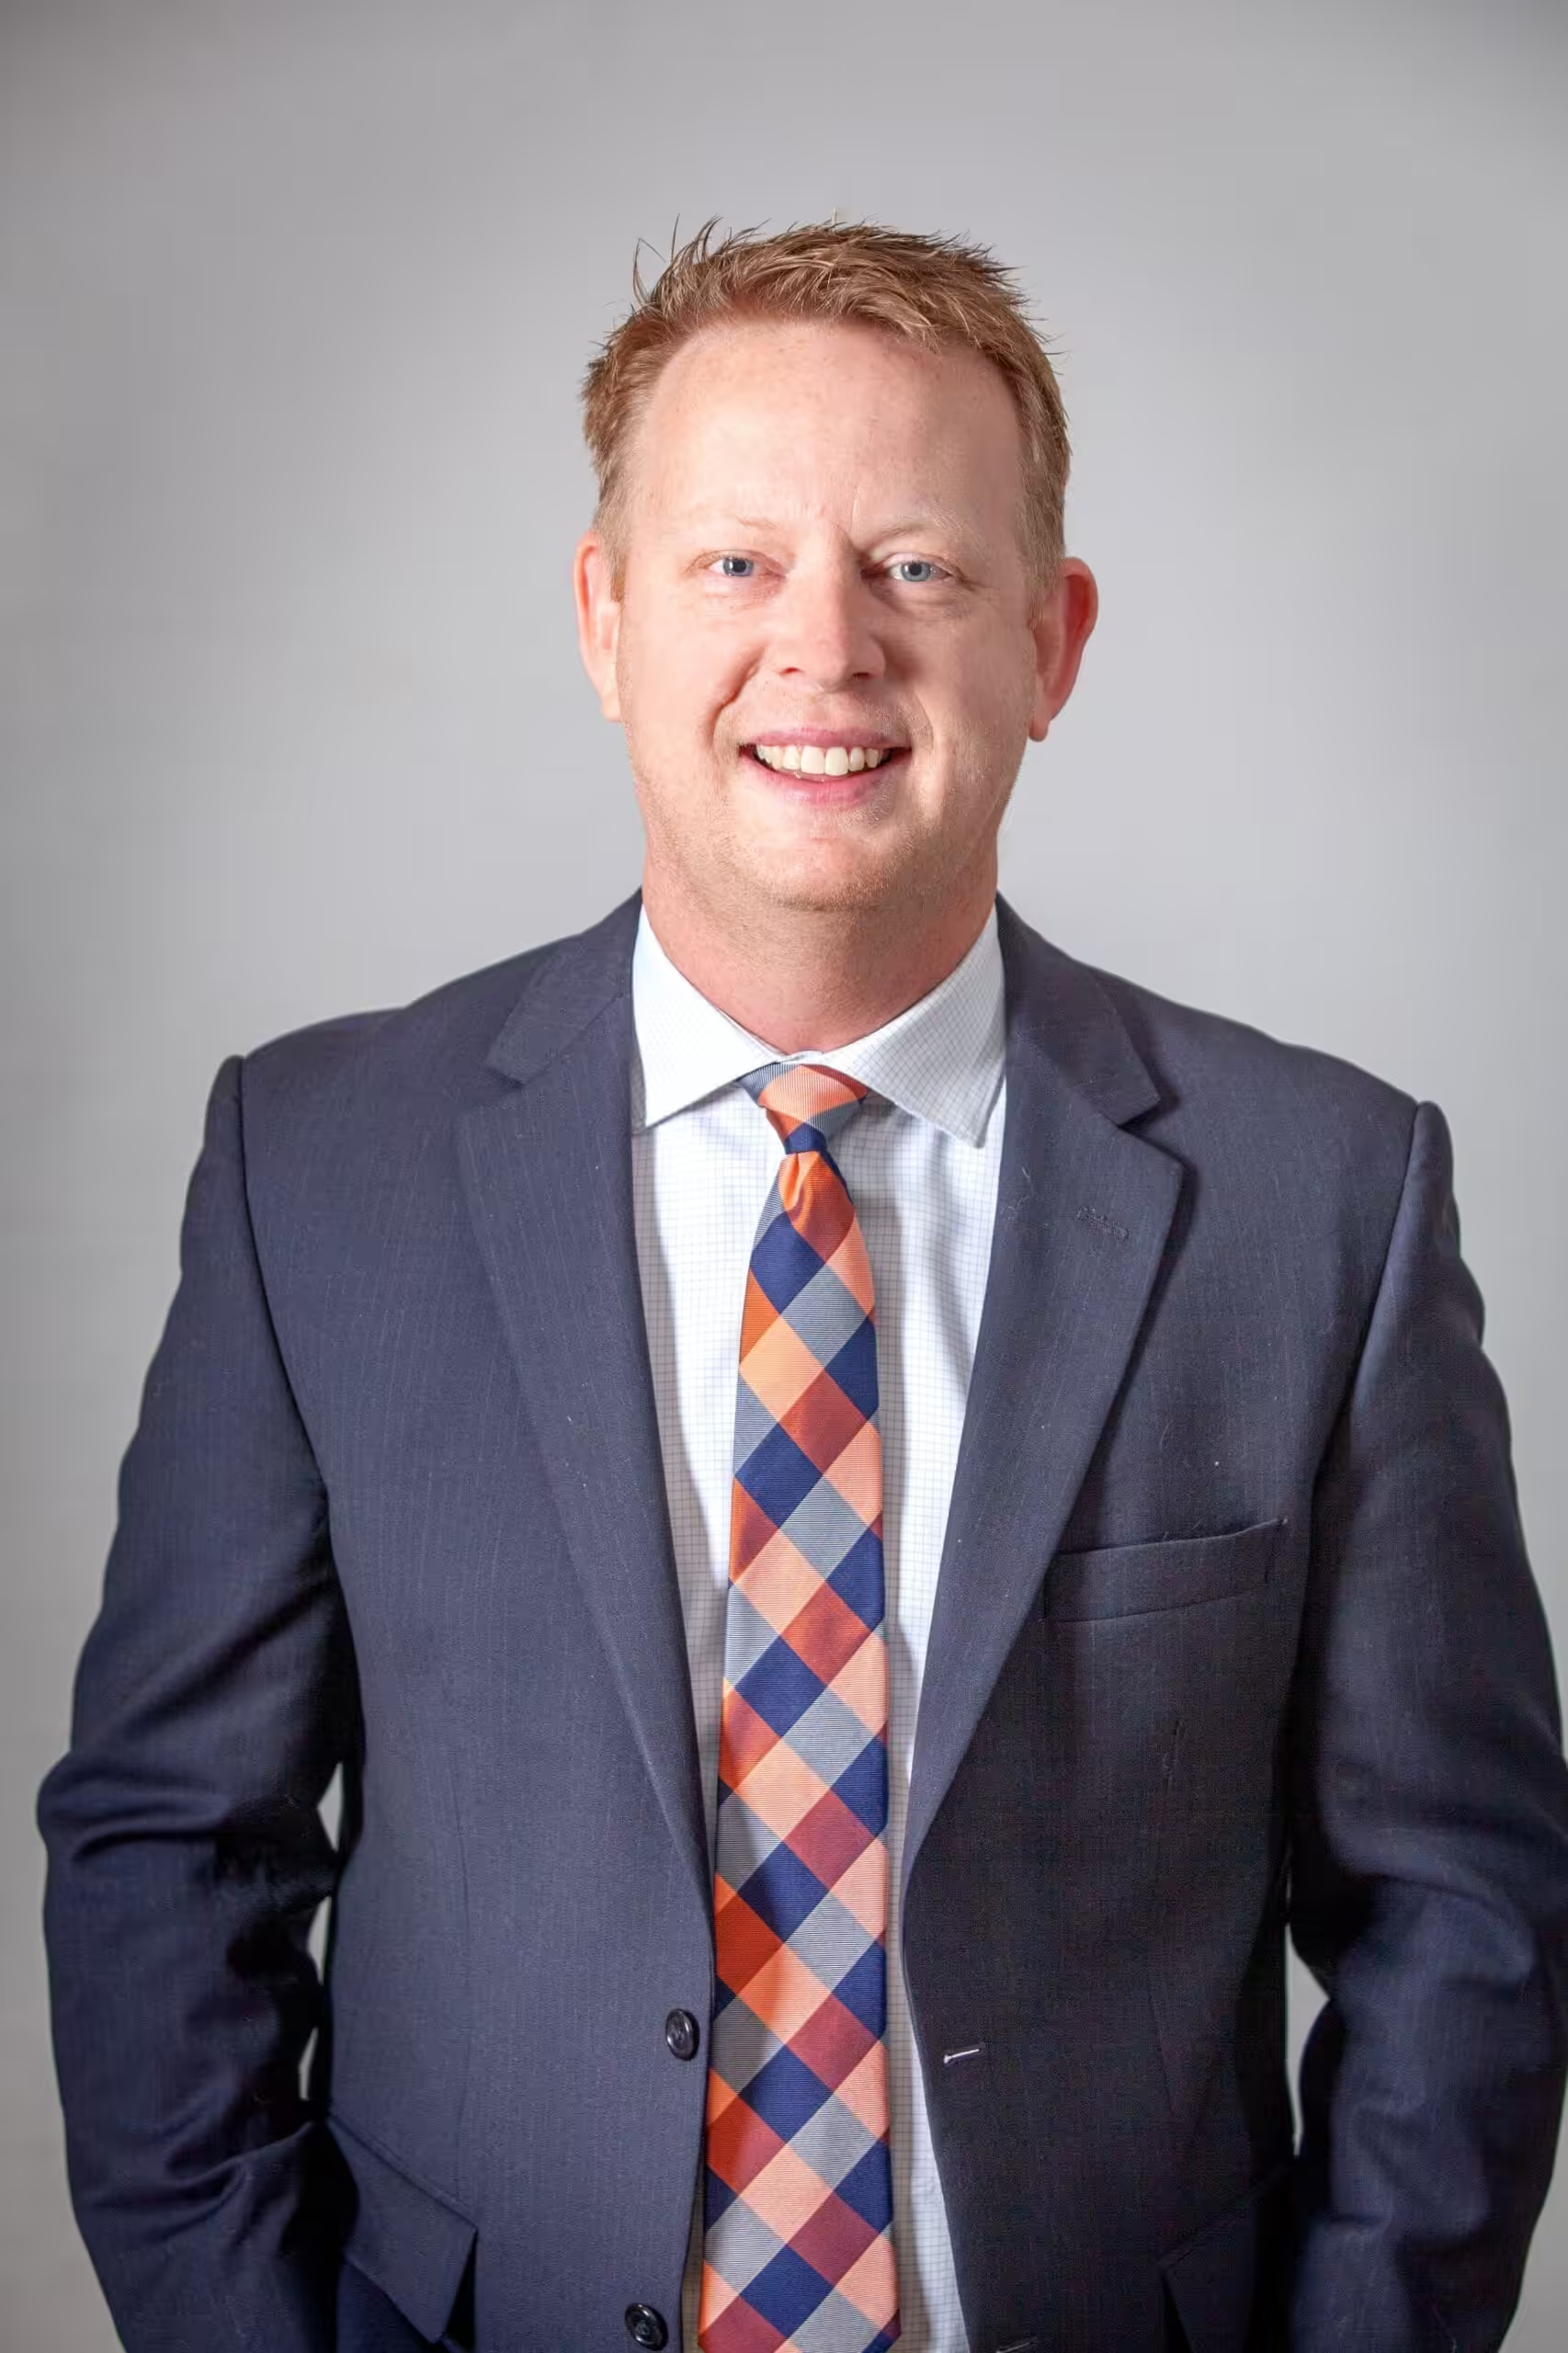
Jeff Wood represents consumers exclusively, never creditors or collectors. He holds federal court admissions across 9 districts, including all courts of AR, CO, NM, and TX. He practices from Little Rock, AR.