United Recovery Systems has run collection accounts nationwide for decades. If a medical bill, credit card, or loan is behind and they’re calling, you are not alone. This page covers who they are, what federal law limits their calls, and what court records show.
Key Takeaways
- United Recovery Systems is a Houston-based debt collector founded in 1977.
- The company has faced an FTC enforcement action and multiple FDCPA class actions.
- You can request debt validation and send a written cease-and-desist letter.
- FDCPA violations can carry statutory damages up to $1,000, plus TCPA damages of $500 to $1,500 per call.
Free Case Review: +1-844-638-1122
What Is United Recovery Systems?
United Recovery Systems is a third-party debt collector founded in 1977. The firm is headquartered at 5800 N Course Dr., Houston, TX. It has also operated under the name Alltran Financial.
- Related companies include J.C. Christensen and Associates, Enterprise Recovery Systems, and CareCall
- A fuller company profile is also available from Goldenberg Firm’s collector directory
United Recovery Systems is a collector, not your original creditor. The debt it references may be inaccurate, outdated, or already resolved.
Why Is United Recovery Systems Calling You?
United Recovery Systems is calling you because a creditor placed, sold, or assigned your account for collection. The call alone does not confirm the debt is yours or accurate. In our practice, we often see notices listing a “current amount due” without saying if interest still accrues.
- Frequent calls throughout the day, sometimes from different numbers
- Voicemails referencing a debt without naming the original creditor
- Letters demanding payment before validation is provided
- Threats of legal action, arrest, or wage garnishment
- Contact with your employer, relatives, or coworkers about the debt
Has United Recovery Systems Been Sued Before?
Yes. United Recovery Systems has faced multiple federal actions over its letters and calling practices. Regulators and courts have repeatedly examined whether its notices meet FDCPA requirements.
In 2002, the FTC required the company to pay $240,000 to settle FDCPA charges. The allegations included improper contact times and false threats of arrest or garnishment. Details appear in the FTC’s press release.
What Do the Class Action Cases Allege?
The class action cases allege letter-disclosure and privacy errors in United Recovery Systems’ mailings. In Ebner v. United Recovery Systems, LP, a consumer alleged letters exposed account data through the glassine window.
A court granted final settlement approval in 2016. United Recovery Systems denied wrongdoing as part of that settlement.
Four more proposed class actions followed in 2017, each alleging unclear collection notices:
- Saroza v. United Recovery Systems, LP: a letter omitted required IRS exceptions for forgiven debt
- Gyokchyan v. United Recovery Systems, LP: a notice failed to state when the balance was calculated
- Karimov v. United Recovery Systems, LP: a similar claim about an unclear “current amount due”
- Bendez v. United Recovery Systems, LP and a companion case: undisclosed non-interest fees in collection letters
A filing alone does not confirm a court found the company liable in any of these 2017 cases.
Two earlier cases also appear in the company’s history. Russo v. United Recovery Systems, LP named the company directly. Goodwyn v. Capital One involved United Recovery Systems as account servicer.
You can browse further filings on the ClassAction.org case archive.
What Debt Collectors Legally Cannot Do
The FDCPA sets firm limits on how United Recovery Systems can pursue a debt. Violating these rules can expose the collector to statutory damages and possibly your attorney’s fees.
- Call repeatedly with intent to annoy or harass
- Use obscene, profane, or abusive language
- Threaten arrest or legal action they do not intend to take
- Falsely claim to be an attorney or government official
- Discuss your debt with third parties beyond limited exceptions
- Continue contact after you send a valid cease and desist letter
- Misstate the amount, status, or ownership of the debt
Automated dialers and prerecorded messages also fall under the TCPA. A TCPA violation can carry damages of $500 to $1,500 per call.
How Do You Stop United Recovery Systems From Calling?
You have several documented options once you decide the calls need to stop. Each step below builds a record you can use later.
- Request debt validation in writing. United Recovery Systems must send proof of the debt within five days of first contact.
- Send a cease and desist letter. Use certified mail with return receipt so you can prove delivery.
- Document every call. Record the date, time, caller name, and content of each conversation.
- Dispute inaccurate credit reporting. The FCRA requires collectors to report accurate information to the bureaus.
What Wood Firm PLLC Can Do About United Recovery Systems
Our firm reviews collection letters and call logs for potential FDCPA and TCPA violations. In our practice, an attorney-sent cease and desist letter often stops calls faster than a consumer’s own letter.
FDCPA and TCPA claims are typically handled on contingency. You generally owe no attorney fees unless we recover compensation for you.
Call The Wood Firm PLLC at +1-844-638-1122 for a free case review. You can also reach us through our contact page.
Where Can You Report United Recovery Systems?
Filing complaints creates an official record of the company’s conduct. Regulators track complaint volume when deciding whether to investigate a collector.
- Consumer Financial Protection Bureau at consumerfinance.gov/complaint
- Federal Trade Commission at reportfraud.ftc.gov
- Your state Attorney General’s consumer protection office
- Your state’s debt collector licensing board, where applicable
Frequently Asked Questions
Can United Recovery Systems call you multiple times a day?
Yes, repeated daily calls can violate the FDCPA if the frequency appears intended to harass you. Courts weigh call volume, whether messages are left, and whether calls continued after a stop request.
Can United Recovery Systems sue you for an unpaid debt?
Yes, a debt collector can file suit to try to collect a valid debt. Respond to any court papers by the deadline listed, since ignoring them can lead to a default judgment.
Can you be arrested for owing United Recovery Systems money?
No, debt is a civil matter, not a criminal one. A threat of arrest over unpaid debt may itself violate the FDCPA, so document it.
Does paying United Recovery Systems remove it from your credit report?
Not automatically, since a payment does not erase an existing entry by itself. You can request a “pay for delete” agreement in writing. Our firm can review it before you pay.
What Should You Do Next?
Request written validation before you pay United Recovery Systems anything. Keep a record of every call, letter, and text you receive.
If contact continues after you assert your rights, The Wood Firm PLLC can review your documentation for free. Call +1-844-638-1122 to discuss your situation.
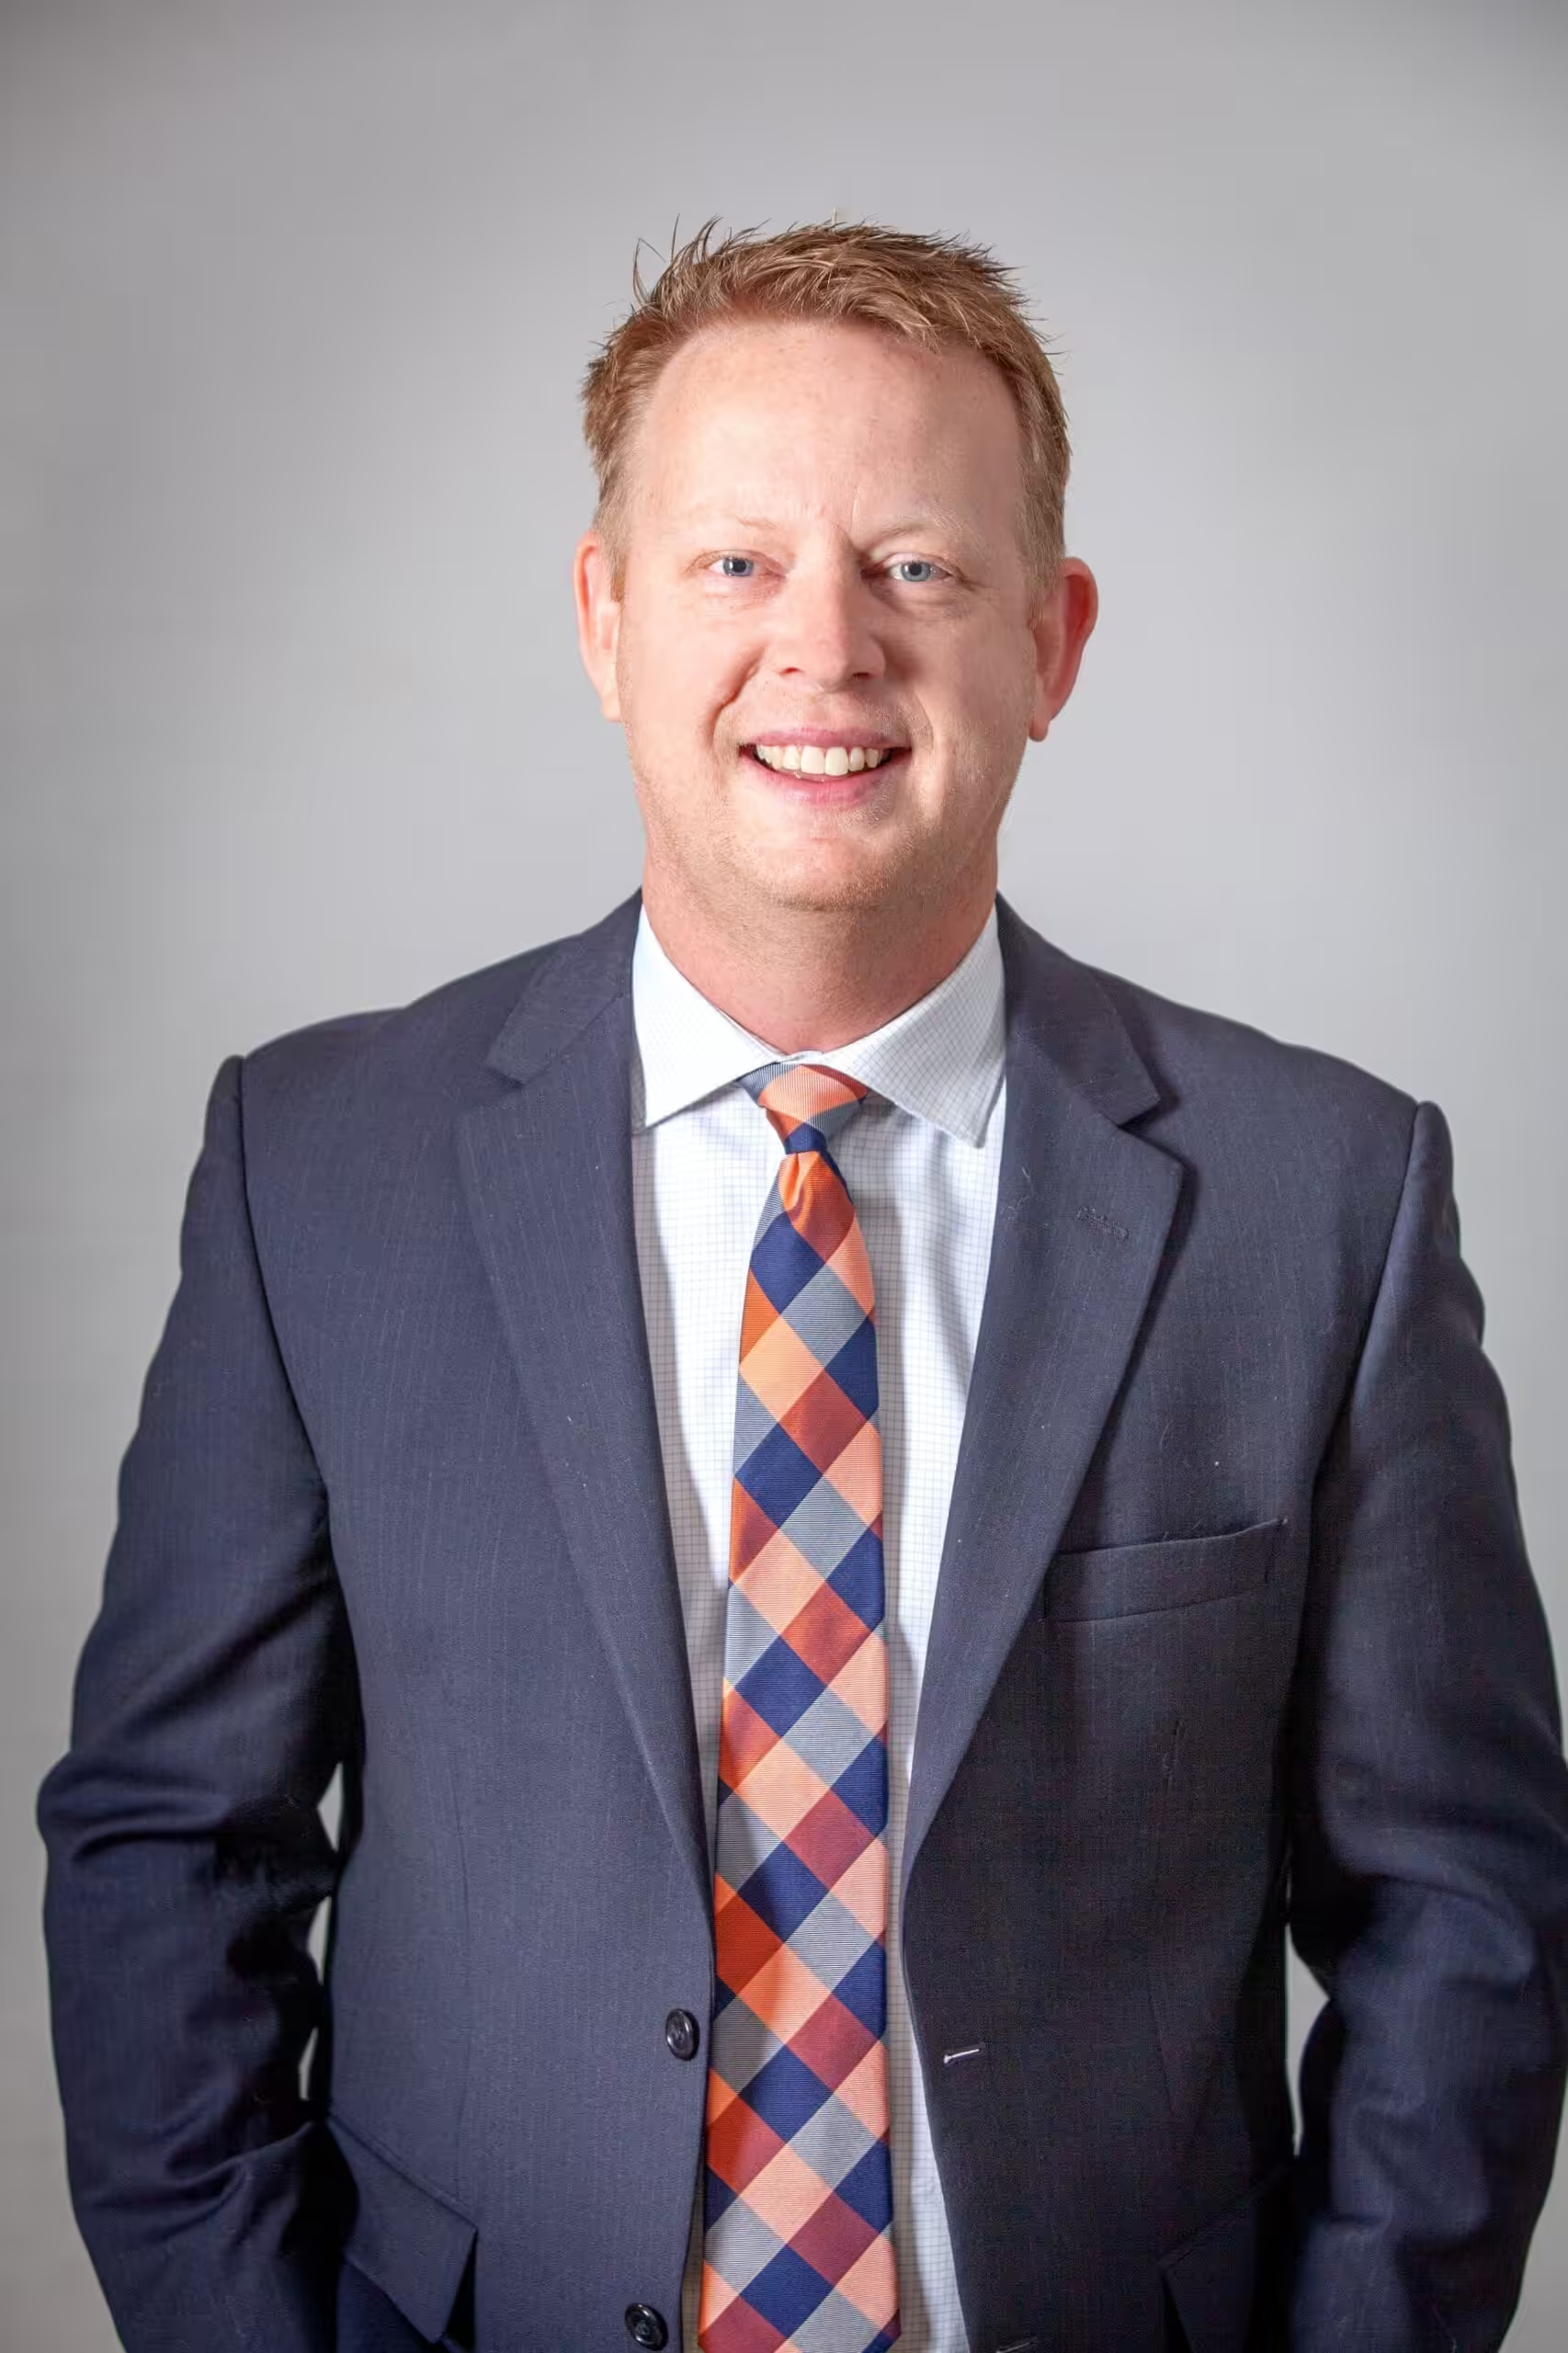
Jeff Wood represents consumers exclusively, never creditors or collectors. He holds federal court admissions across 9 districts, including all courts of AR, CO, NM, and TX. He practices from Little Rock, AR.