If a debt collector called your Nevada workplace without permission, threatened to seize exempt property, or placed a collection account on your credit report before sending a written notice, each of those acts may be a standalone federal violation. According to CFPB complaint data and Nevada Financial Institutions Division records, these are the most frequently alleged patterns against collectors operating in Nevada. Call +1-844-638-1122 for a free case review with The Wood Firm PLLC.
Key Takeaways
- Nevada requires all third-party debt collectors to hold an active license through the Nevada Financial Institutions Division. Operating without one may be a violation from the first call made to a Nevada resident.
- Nevada’s statute of limitations on written contracts, including credit cards and medical bills, is four years. Threatening to sue on older debts may constitute false representations under the FDCPA.
- According to CFPB complaint data, Nevada consumers have allegedly reported repeated workplace calls, threats against exempt property, and credit entries appearing before any written validation notice.
- The FDCPA, FCRA, and TCPA each apply to specific collection behaviors in Nevada. A single auto-dialed call to your cell phone without consent may carry $500 to $1,500 in TCPA damages.
- FDCPA statutory damages reach up to $1,000 per case; TCPA damages run $500 to $1,500 per unauthorized call or text.
- The Wood Firm PLLC handles Nevada consumer protection cases on contingency. No upfront fees. If a collector violated federal law, they pay our fees.
Free Case Review: +1-844-638-1122
What Is the Nevada Fair Debt Collection Practices Act?
The Nevada Fair Debt Collection Practices Act, codified primarily under NRS Chapter 649, mirrors and extends the federal FDCPA by adding state-level obligations. The most consequential is NRS 649.370, which treats any violation of the federal FDCPA as a simultaneous violation of Nevada state law, meaning a single illegal call can trigger both federal and state liability.
Nevada also requires collection agencies to hold a valid license through the Nevada Financial Institutions Division, regardless of where the agency is located. In our practice, the first thing we verify on any Nevada file is whether that license exists, because every contact an unlicensed agency makes may independently violate state law under NRS Chapter 649.
Nevada Financial Institutions Division: Collector Licensing Verification
- Agency: Nevada Financial Institutions Division (FID)
- License Check: fid.nv.gov
- Governing Statute: NRS Chapter 649 (Nevada collection agency licensing and conduct rules)
- FDCPA Cross-Reference: NRS 649.370: any federal FDCPA violation is also a Nevada state violation
- Nevada Bar Referral Service: Nevada State Bar: Collections
- What to request: The collector’s Nevada collection agency license number. Ask for it in writing.
Nevada Debt Collection Laws Every Consumer Should Know
Nevada debt collection laws prohibit calls before 8 a.m. or after 9 p.m. Pacific Time, obscene or threatening language, misrepresentation of a debt’s legal status, and operation without a valid Nevada license. In our practice, the violations that appear most often in Nevada files involve workplace contact, threats against exempt assets, and credit entries that precede written validation notices:
- Workplace calls after you objected. If you told a collector your employer prohibits personal calls and the calls continued, each subsequent call may be a standalone FDCPA violation under 15 U.S.C. § 1692c(a)(3). Identify the date you gave notice and the dates calls continued after.
- Threats against exempt property. Nevada exempts professional tools, one vehicle, and household goods. If a collector named a specific asset that was legally exempt, that threat may have been a false representation under 15 U.S.C. § 1692e.
- Credit entries before written notice. If a collection account appeared on your credit report before you received any letter, that sequence may support both an FDCPA and FCRA claim. Compare the date the entry first appeared to the date on your earliest letter.
What Is the Nevada Statute of Limitations on Debt
Nevada’s statute of limitations on written contracts, including credit card agreements, personal loans, and medical bills, is four years from the date of last payment or default. After that period, collectors may still call and write, but they cannot obtain a court judgment.
When a collector threatens to sue on a debt past Nevada’s four-year limit, that threat may constitute a false representation under 15 U.S.C. § 1692e(5) of the federal FDCPA and, through NRS 649.370, a simultaneous violation of Nevada state law.
One detail collectors rely on consumers missing: making any partial payment on a time-barred Nevada debt can restart the four-year clock entirely. Even a small payment made under pressure can revive a legally unenforceable account. Do not acknowledge or pay an old debt before consulting an attorney about the statute implications for that specific account.
How Las Vegas Work Schedules Affect Your Collection Rights
Las Vegas work schedules affect your collection rights because the FDCPA’s default timing rules (no calls before 8 a.m. or after 9 p.m.) were written for a standard workday, not for casino dealers, hospitality staff, or entertainment workers on rotating shifts. You have the right to notify a collector in writing that a particular time is inconvenient.
Once that notice is given, calling during those hours may be a violation regardless of the federal default window. Collectors also sometimes obtain a casino’s main number and ask to be connected to an employee during a shift, something most casino employers expressly prohibit, and that contact may violate 15 U.S.C. § 1692c(a)(3) if you previously gave notice.
Quick note: If a collector called your workplace after you objected, or cited a garnishment amount on your tips that seemed inflated, those specific facts matter. Call +1-844-638-1122. A free review takes a few minutes and tells you whether there is a case.
Nevada Wage Garnishment Protections
Nevada limits garnishment to the lesser of 25% of disposable earnings per week or the amount by which disposable weekly earnings exceed 50 times the federal minimum wage. Heads of household who provide more than half the support for a dependent receive stronger protection: Nevada caps garnishment at 10% of gross weekly wages.
Social Security, disability payments, Veterans benefits, unemployment compensation, and workers’ compensation are fully exempt, even after being deposited into a bank account, provided the funds are traceable to the exempt source.
Nevada’s homestead exemption protects up to $605,000 in home equity from forced sale for consumer debts, among the highest protections of any state. That exemption does not apply automatically. It must be asserted through a filed homestead declaration. If a collector obtained a judgment and you have not yet recorded that declaration, filing before any execution attempt is time-sensitive.
How to Stop Debt Collector Calls in Nevada
What we examine first
- Nevada FID license status on the date of first contact. Collectors sometimes let licenses lapse between renewal periods. A contact made during a lapse may violate state law even if the agency is currently licensed. We pull the FID database record for the date of your first communication, not just today’s status.
- Call logs, dialer records, and spoofed numbers. We request outbound call records for your account, showing timestamps and numbers used. Spoofed local numbers, designed to resemble a Las Vegas or Reno area code when the caller is out-of-state, appear in these logs and help establish intent.
- Validation letter postmarks and credit report sequencing. We compare the letter date to the actual postmark and compare the date of the first collection entry in your credit file to the date of the earliest written notice. A backdated letter, or a credit entry that predates any written notice, may support claims under both the FDCPA and FCRA.
How contact stops
Once The Wood Firm PLLC enters a notice of representation, collectors must direct all further contact to our office and cease communicating with you directly. If contact continues after that notice, each additional call or letter may be a standalone violation added to your claim.
Which laws apply
- FDCPA (15 U.S.C. §§ 1692 et seq.) and NRS 649.370. Applies to workplace calls made after you gave notice, lawsuit threats on time-barred debts, and backdated validation letters. Under NRS 649.370, every federal FDCPA violation is simultaneously a Nevada state violation, potentially expanding available remedies. Statutory damages reach $1,000 per case; attorney fees are paid by the collector if we prevail.
- FCRA (15 U.S.C. §§ 1681 et seq.). Applies when a collection account appears on your credit report before you received a written validation notice, or when a dispute was not investigated. Willful violations carry $100 to $1,000 per violation plus potential punitive damages.
- TCPA (47 U.S.C. § 227). Applies when a collector used an automatic dialer or prerecorded message to reach your cell phone without prior express consent. Each unauthorized auto-dialed call carries $500 to $1,500 in statutory damages.
There are no upfront fees. The Wood Firm PLLC handles Nevada consumer protection cases on a contingency basis. If a collector violated federal law, the FDCPA requires them to pay our attorney fees. You pay nothing regardless of how the case resolves.
Attorney Jeff Wood
Jeff Wood founded The Wood Firm PLLC after working inside a debt collection agency, an experience that gave him a direct understanding of how collection operations actually function rather than how they describe themselves in court filings. For more than 15 years, he has represented consumers exclusively, never a creditor or collection agency.
He is admitted to practice in all federal courts in Arkansas, Colorado, New Mexico, and Texas, as well as the Southern District of Indiana, Eastern District of Michigan, Eastern District of Missouri, Western District of Tennessee, and Western District of Wisconsin, with Of Counsel relationships extending coverage to more than 12 additional states.
He earned his law degree from the University of Arkansas School of Law and operates the firm from Little Rock. On every Nevada file, he reviews the call logs, dialer records, and chain-of-title documentation personally, because those are where Nevada collectors most commonly cut corners.
If a Nevada debt collector has crossed a line, in a call, a letter, or on your credit report, call +1-844-638-1122 for a free case review. The Wood Firm PLLC handles these cases on contingency. If they violated federal law, they pay our fees.
Nevada Debt Collection Frequently Asked Questions
Is debt collection legal in Nevada? Yes, but collectors must hold a valid Nevada Financial Institutions Division license under NRS Chapter 649 and comply with both the federal FDCPA and Nevada’s Fair Debt Collection Practices Act. Under NRS 649.370, any violation of the federal FDCPA is also a violation of Nevada state law. An unlicensed agency may be violating state law from its first call to a Nevada resident.
What is the statute of limitations on debt in Nevada? Nevada’s statute of limitations on written contracts, including credit cards and medical bills, is four years from the date of last payment or default. After that period, collectors cannot obtain a court judgment, and threatening to sue on a time-barred debt may violate 15 U.S.C. § 1692e(5) of the FDCPA.
Can a debt collector call my workplace in Nevada? A collector can call your workplace only if your employer has not prohibited such calls. Once you notify the collector that your employer prohibits personal calls, further workplace contact may violate 15 U.S.C. § 1692c(a)(3). Each call after that notice may be a standalone FDCPA violation.
What damages can I recover for FDCPA violations in Nevada? FDCPA violations carry statutory damages of up to $1,000 per case plus actual damages and attorney fees paid by the collector. TCPA violations involving auto-dialed calls carry $500 to $1,500 per unauthorized call. FCRA willful violations carry $100 to $1,000 per violation plus potential punitive damages.
How do I verify a Nevada debt collector’s license? Check the Nevada Financial Institutions Division at fid.nv.gov. Ask the collector for their license number in writing and confirm it independently in the FID database. An absent or lapsed license may serve as evidence in a federal or state claim.
The Wood Firm PLLC has handled Nevada consumer protection files involving unlicensed collection agencies, workplace calls to casino and hospitality workers, threats against exempt property, and credit entries that appeared before any written validation notice.
The firm handles these cases on contingency, with no upfront fees, and if a collector violates federal law, they pay our fees. Call +1-844-638-1122 for a free case review.
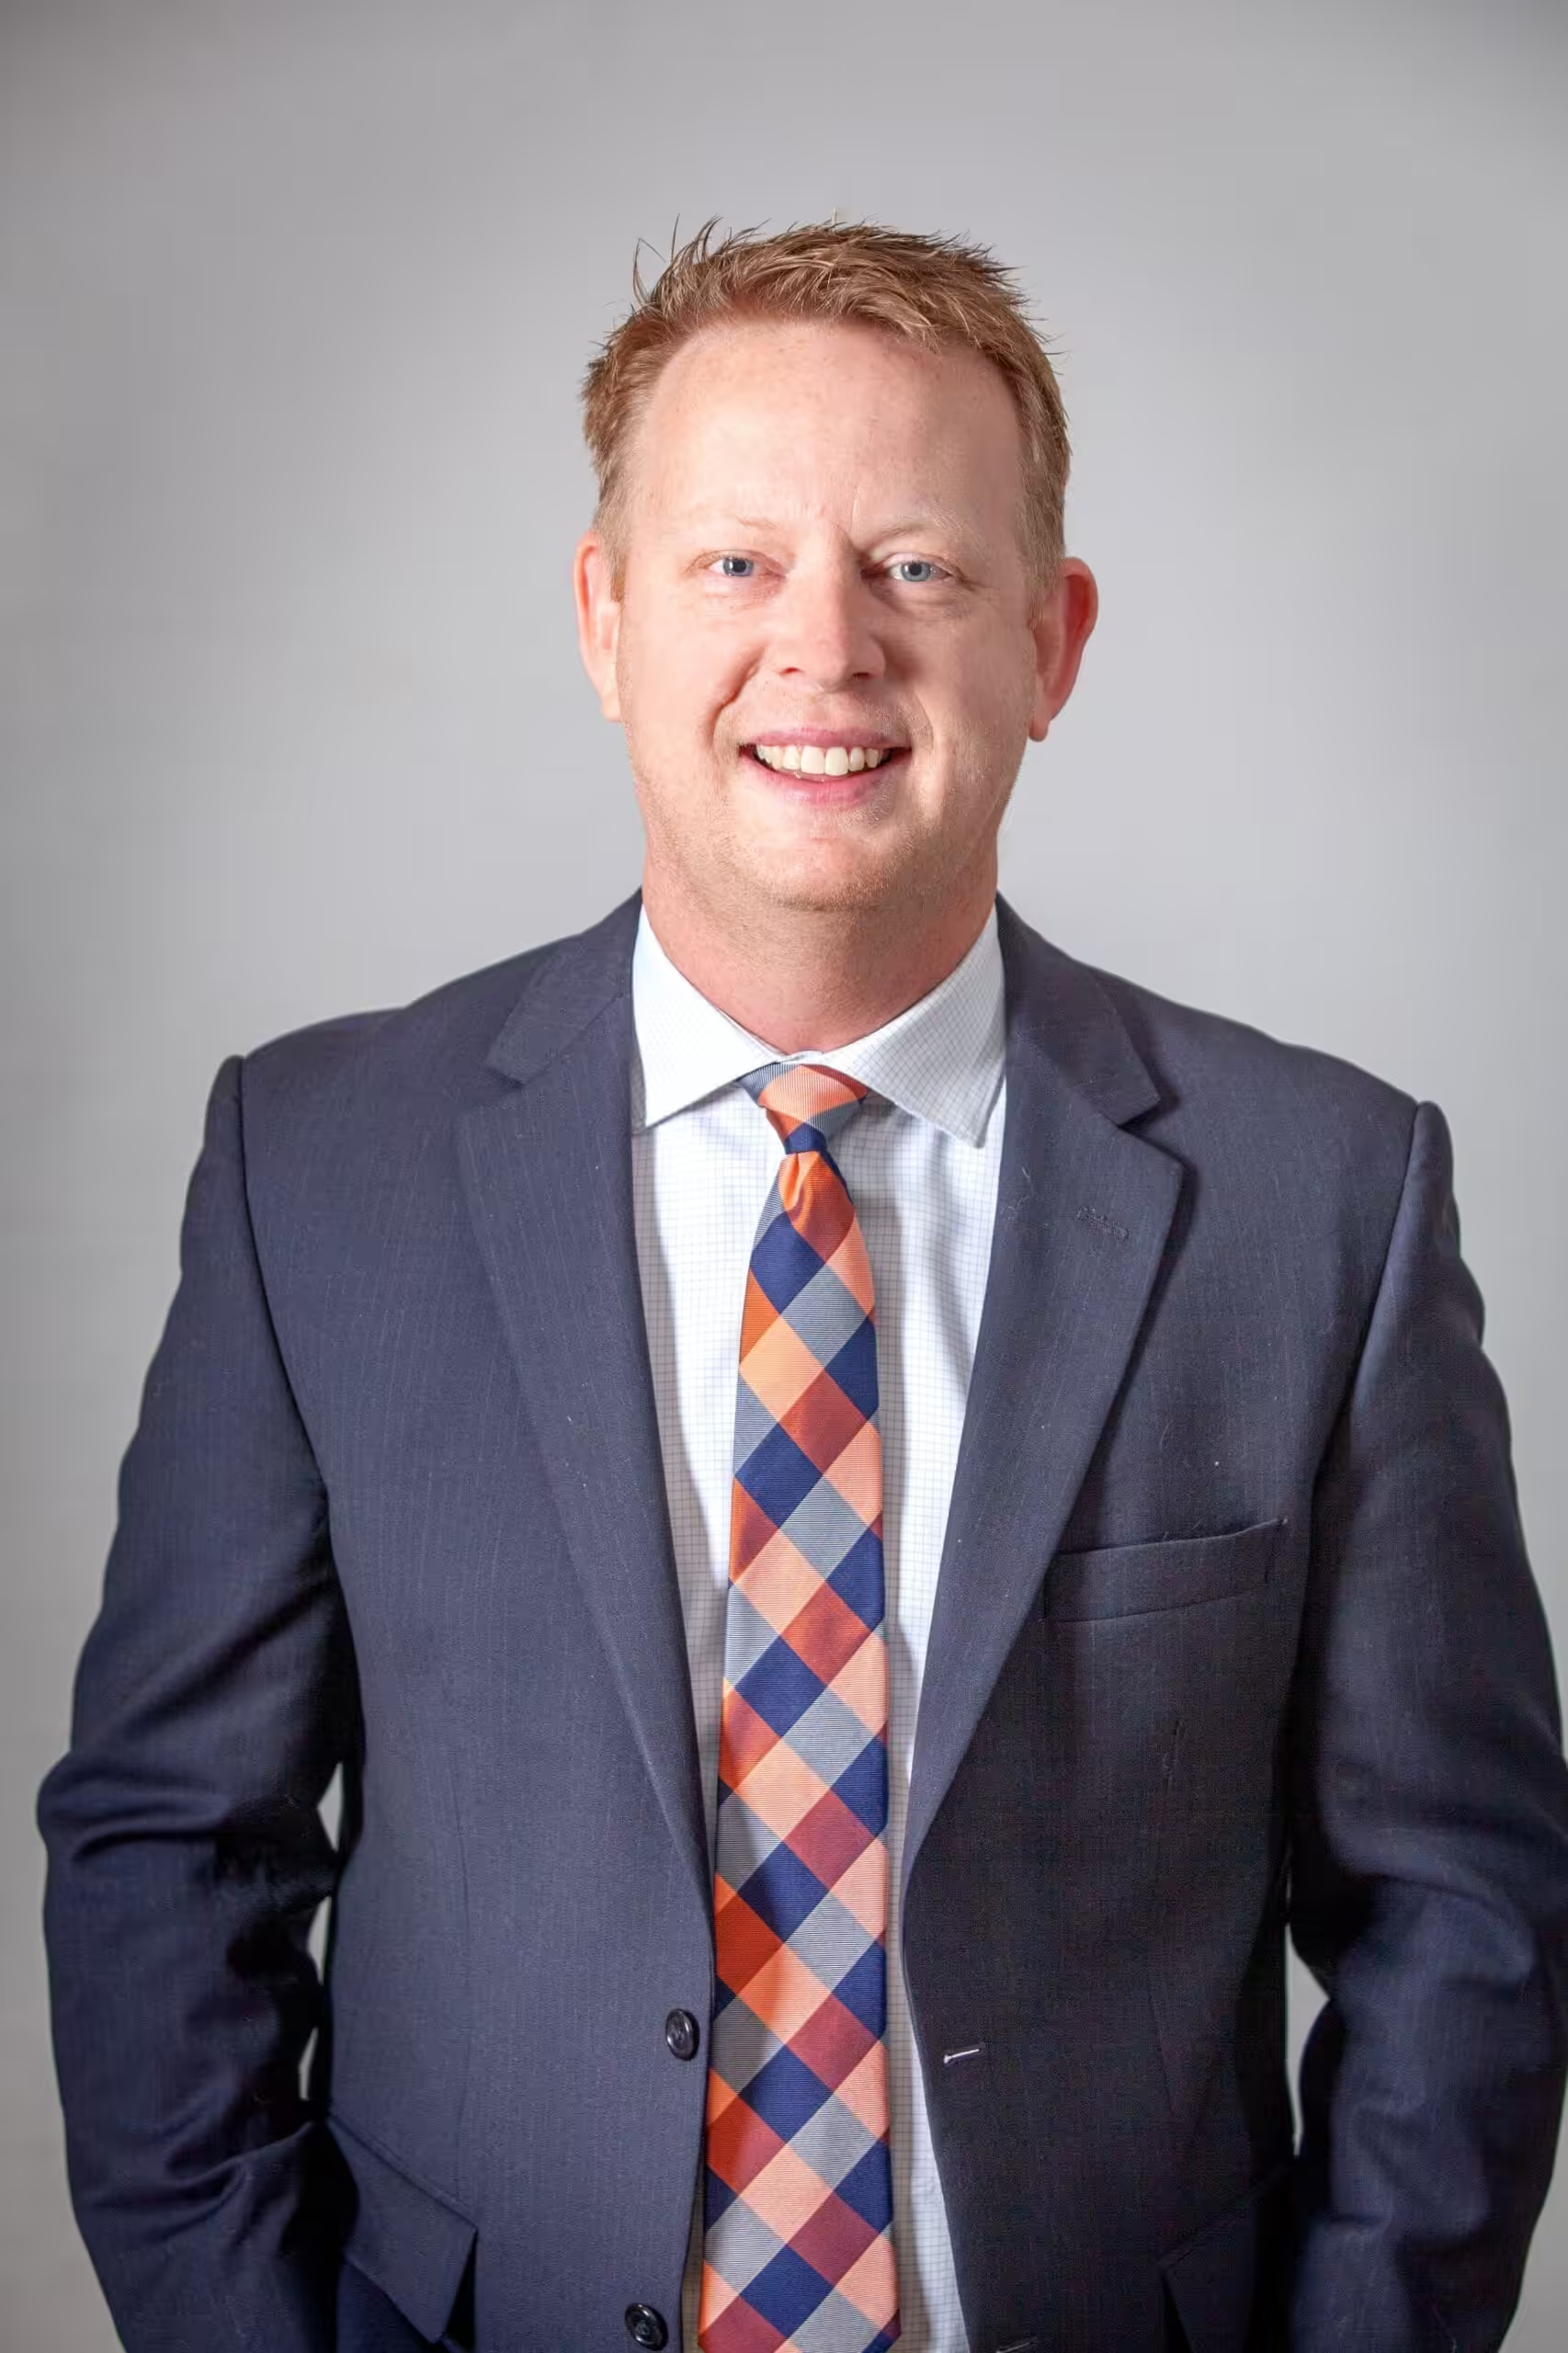
Consumer protection attorney. 15+ years exclusively representing consumers against debt collectors. Admitted in federal courts across 9 districts. The Wood Firm PLLC, Little Rock, AR.