United Collection Bureau contacts consumers about debts they may not recognize, often calling multiple times a day from rotating numbers before any written validation notice arrives. According to BBB complaint records, UCB has accumulated more than 41 consumer complaints, with filers reportedly describing workplace calls, threats of wage garnishment, and prerecorded messages on cell phones. Those documented patterns each map directly onto violations of federal consumer protection law.
Key Takeaways
- UCB (United Collection Bureau Inc.) is headquartered at 5620 Southwyck Blvd., Toledo, OH 43614 and has operated since 1959, collecting for banks, hospitals, utilities, and telecoms.
- Federal court records show UCB as a named defendant in multiple FDCPA lawsuits, with filings alleging misleading balance disclosures, deceptive settlement deadlines, and failure to provide required notices.
- According to BBB and CFPB complaint data, the most frequently reported patterns include excessive daily calls, alleged workplace contact after requests to stop, and alleged threats of immediate wage garnishment.
- The FDCPA, FCRA, and TCPA each apply to UCB’s documented conduct. Each statute carries its own damages track independent of the others.
- FDCPA violations carry up to $1,000 per claim. TCPA violations carry $500 to $1,500 per call. FCRA violations carry $100 to $1,000 per willful inaccuracy.
- The Wood Firm PLLC takes these cases on contingency. If UCB violated federal law, they pay attorney fees.
Free Case Review: +1-844-638-1122
Who Is United Collection Bureau
United Collection Bureau is a third-party debt collection agency based in Toledo, Ohio. They purchase charged-off accounts from original creditors and attempt to recover the full stated balance. UCB has operated since 1959 and collects for banks, credit card issuers, healthcare providers, utility companies, and telecommunications carriers.
- Also Known As: UCB, UCB Inc., United Collection Bureau Inc.
- Address: 5620 Southwyck Blvd., Suite 206, Toledo, OH 43614
- Phone: 866-209-0622 | (866) 209-0622 | +1 866-209-0622 | 8662090622
- Website: ucbinc.com
- BBB Profile: United Collection Bureau BBB listing
UCB buys charged-off debt portfolios for pennies on the dollar, then attempts to collect the full amount. In our practice, we pull the chain-of-title documentation on every UCB file first, because that is where purchased debt accounts most commonly fail validation. A broken or missing chain of title means UCB may have no legal standing to collect the account at all.
United Collection Bureau Phone Numbers to Watch For
UCB operates from multiple outbound lines and rotates them regularly. Consumers reporting these numbers to the BBB and CFPB have identified the following as active UCB contact numbers:
- 877-570-0411 | (877) 570-0411 | +1 877-570-0411 | 8775700411
- 877-570-0405 | (877) 570-0405 | +1 877-570-0405 | 8775700405
- 866-769-4048 | (866) 769-4048 | +1 866-769-4048 | 8667694048
- 877-205-7960 | (877) 205-7960 | +1 877-205-7960 | 8772057960
- 800-761-5394 | (800) 761-5394 | +1 800-761-5394 | 8007615394
- 800-867-3104 | (800) 867-3104 | +1 800-867-3104 | 8008673104
- 888-520-1845 | (888) 520-1845 | +1 888-520-1845 | 8885201845
UCB rotates these numbers to reduce call-blocking by consumer apps. Rotation does not change your rights. Log every call with the date, time, inbound number, and a summary of what the caller said. Visit the firm’s guide on how to document debt collection harassment correctly before the next call comes in.
Why Is United Collection Bureau Calling You
United Collection Bureau is calling you because a creditor assigned or sold your account to them for collection. The original creditor charged off the account after roughly 120 to 180 days of non-payment, then transferred the balance to UCB at a fraction of face value.
UCB’s margin depends on recovering the full amount you allegedly owe. That financial pressure drives the call volume many consumers report. Receiving their calls does not confirm you owe the debt or that the amount is accurate.
Request written debt validation before acknowledging or paying anything. Federal law requires UCB to send a written notice within five days of first contact. If that notice never arrived, the gap itself may support an FDCPA claim.
UCB Collection Tactics That May Violate Federal Law
UCB collection tactics consumers have reportedly described to the BBB and CFPB include patterns that map directly onto FDCPA prohibitions. The following behaviors, if documented, each constitute a potential standalone violation.
- Calling before 8 AM or after 9 PM local time
- Contacting consumers at their workplace after being told to stop
- Calling multiple times in a single day
- Allegedly threatening arrest or criminal prosecution for a civil debt
- Claiming immediate wage garnishment without holding a court judgment
- Allegedly using prerecorded or autodialed messages to cell phones without prior written consent
- Failing to identify themselves as a debt collector at the start of each call
- Allegedly discussing the debt with third parties, including family or coworkers
- Continuing to call after receiving a written cease-and-desist
In our experience, UCB voicemail messages frequently omit the required disclosure that the caller is a debt collector attempting to collect a debt. That specific omission sits at the center of FDCPA claims under 15 U.S.C. 1692e(11). If you saved any UCB voicemails, those recordings may already hold the evidence needed to open a case.
Is United Collection Bureau a Scam
United Collection Bureau is a real, licensed debt collection agency, but licensed does not mean every tactic is legal. UCB holds active state licensure and has operated since 1959, which distinguishes them from impersonation scams that fabricate collector identities.
Consumers should still verify any contact before discussing an account. Legitimate collectors must provide written debt validation on request. If a caller claiming to be UCB refuses to supply a mailing address, cannot identify the original creditor, or demands payment by gift card or wire transfer, treat that contact as fraudulent and do not provide personal information.
In our practice, we examine every UCB collection letter for the disclosures required under 15 U.S.C. 1692g, because missing or defective validation language in that letter is one of the most reliable entry points into an FDCPA claim. Similar patterns of licensed-but-aggressive conduct have appeared at Regional Adjustment Bureau, and the same legal framework applies to UCB.
How to Spot a Fake Caller Impersonating UCB
Scammers sometimes use real agency names to pressure consumers into paying debts that do not exist. Use these checks to confirm the caller is actually UCB before engaging with the account.
- Ask for the caller’s full name, company name, and mailing address. A real collector supplies all three. A scammer typically stalls or refuses.
- Request a written validation notice. Legitimate collectors must send one within five days. Scammers avoid leaving a paper trail.
- Do not confirm personal details the caller does not already have. Scammers use UCB’s name to fish for Social Security numbers and bank information.
- Verify the call independently. Hang up and dial UCB’s published main line at 866-209-0622. Never call back using a number the original caller provided.
- Reject any demand for gift card or wire transfer payment. Real debt collectors accept standard payment methods. Gift card demands confirm fraud.
Is United Collection Bureau Banned by the FTC
No. United Collection Bureau has not received an FTC ban or consent order as of the date of this article. No permanent injunction against UCB appears in the FTC’s public enforcement records.
That absence does not mean UCB operates without oversight. The CFPB maintains a public complaint database that includes UCB entries, and the Ohio Attorney General has concurrent jurisdiction over state consumer protection violations. In our practice, we review the CFPB complaint database on every UCB file, because recurring complaint categories across many consumers signal a systemic policy failure rather than an isolated incident, and systemic failures support class or pattern claims in addition to individual FDCPA actions.
Has United Collection Bureau Been Sued in Federal Court
Yes. United Collection Bureau has been named as a defendant in multiple federal FDCPA lawsuits. Court filings allege a pattern of disclosure failures and deceptive collection communications.
- Leitner v. United Collection Bureau, 1:17-cv-01085: Filings allege false and deceptive collection practices under 15 U.S.C. 1692e.
- Lugo v. United Collection Bureau, 1:17-cv-00512: Court filings allege UCB omitted required disclosures and threatened fees not authorized by law.
- Gueta v. United Collection Bureau, 1:17-cv-02401: Filings allege UCB stated a “current balance” without disclosing that interest could increase the amount owed.
- Stern v. United Collection Bureau, 2:18-cv-00190: Court filings allege UCB used misleading settlement deadlines to pressure consumers into payment.
- Umana v. United Collection Bureau, 1:18-cv-00640: Filings allege UCB failed to provide sufficient information for a consumer to calculate the total amount owed.
When we open a UCB file, we pull the collection letter and any validation notice first. The Gueta and Stern theories apply directly to balance disclosure and settlement language. If the letter in your file mirrors those defects, you may already hold a viable claim before any further investigation.
What Federal Laws Apply to UCB Debt Collection
Three federal statutes apply directly to UCB’s documented conduct. Each carries its own damages track.
- Fair Debt Collection Practices Act (FDCPA): Applies to every third-party collector, including UCB. Violations of call-hour limits, disclosure requirements, or the prohibition on false threats each carry up to $1,000 in statutory damages plus attorney fees paid by UCB if you prevail.
- Fair Credit Reporting Act (FCRA): Governs how UCB reports your account to the credit bureaus. Inaccurate balances, wrong account statuses, or entries that persist after a valid dispute each constitute furnisher violations carrying $100 to $1,000 per willful inaccuracy.
- Telephone Consumer Protection Act (TCPA): Applies if UCB used an autodialer or prerecorded message to call your cell phone without prior written consent. Each unauthorized call carries $500 in statutory damages, rising to $1,500 for willful violations.
How to Stop United Collection Bureau from Calling You
You have three legally recognized options to stop UCB calls. Each triggers specific federal obligations on UCB’s side.
- Send a written cease-and-desist. Under 15 U.S.C. 1692c(c), once UCB receives your written demand to stop telephone contact, they may only call once more to confirm they will stop or to notify you of specific legal action. Send by USPS certified mail with return receipt. Every call UCB makes after receipt is a standalone FDCPA violation.
- Request written debt validation. Submit a validation request within 30 days of first contact. UCB must halt all collection activity until they verify ownership of the debt and the accuracy of the stated balance. If they cannot verify both, collection must cease permanently.
- Retain legal counsel. Once UCB receives notice that you have an attorney, they must direct all contact to counsel and stop calling you directly. This option typically stops UCB contact within 48 hours of the attorney notification.
How to File a Complaint Against United Collection Bureau
Filing complaints creates a public record and triggers regulatory attention. Submit to all four of the following for maximum effect.
- Consumer Financial Protection Bureau: File at consumerfinance.gov/complaint. The CFPB forwards your complaint to UCB and requires a response within 15 days. All submissions enter the public complaint database that federal regulators use to identify enforcement targets.
- Federal Trade Commission: Report at ReportFraud.ftc.gov. The FTC uses complaint volume to identify patterns and build enforcement cases. Individual reports do not generate direct responses, but accumulated volume triggers investigations.
- Ohio Attorney General: File at ohioattorneygeneral.gov. UCB is headquartered in Toledo, giving the Ohio AG direct jurisdiction and the authority to pursue state consumer protection violations alongside federal ones.
- Better Business Bureau: File at bbb.org. BBB complaints appear publicly and factor into UCB’s rating, which consumers and attorneys review when evaluating the agency’s conduct history.
Regulatory complaints and private lawsuits run concurrently, not exclusively. Filing with the CFPB or FTC does not waive your right to sue UCB under the FDCPA, TCPA, or FCRA. A skilled consumer protection attorney can pursue both tracks simultaneously.
Can United Collection Bureau Sue You or Garnish Your Wages
Yes, UCB can file a civil lawsuit, but only if the debt is within your state’s statute of limitations and UCB holds adequate documentation of ownership and the original balance. Most states set a four-to-six-year window on credit card and medical debt. Time-barred debts cannot support a court judgment.
UCB cannot garnish wages without first suing you, winning a judgment, and completing the state garnishment process. Any UCB representative who claims they will garnish your paycheck on the next call is allegedly making a threat they cannot execute without a court order. That specific statement is a violation of 15 U.S.C. 1692e(4) and produces a standalone FDCPA claim.
How to Remove United Collection Bureau from Your Credit Report
Yes, UCB can report a collection account to Equifax, Experian, and TransUnion, but that reporting must comply with the FCRA. A UCB entry can remain for up to seven years from the original delinquency date, not from the date UCB acquired the debt.
Pull your free reports at AnnualCreditReport.com. Look for an incorrect balance, wrong account status, inaccurate open date, or a duplicate entry for the same debt. Any of those conditions qualifies as a furnisher error under the FCRA.
Send a written dispute to each bureau showing the inaccuracy with supporting documentation. The bureau must investigate and respond within 30 days. If UCB cannot verify the entry’s accuracy, the bureau must delete or correct it. Re-insertion of a deleted entry without five-day notice to you is itself a standalone FCRA violation.
How The Wood Firm PLLC Helps Stop UCB Debt Harassment
The Wood Firm PLLC represents consumers in FDCPA, FCRA, and TCPA claims against collectors like United Collection Bureau. When a UCB file comes in, we pull the chain-of-title documentation, the collection letters, the validation correspondence, and the credit report entry at the same time, because UCB’s exposure frequently spans all three federal statutes and each requires its own evidentiary record.
We work exclusively on contingency, representing consumers only, never creditors or collectors. After you contact us, UCB must route all communications to our office and stop contacting you directly. Call The Wood Firm PLLC at +1-844-638-1122 for a free case review.
If UCB called your workplace, sent robocalls to your cell, or posted inaccurate data on your credit report, visit our contact page or call +1-844-638-1122 for a free case review. The Wood Firm PLLC handles these cases on contingency. If they violated federal law, they pay our fees.
Frequently Asked Questions About UCB
Why does UCB keep calling from different numbers
UCB rotates outbound numbers to reduce the chance that call-screening apps block their lines. Number rotation does not change your FDCPA rights. Document every call regardless of which number UCB uses.
What is UCB calling you about
UCB is calling because a creditor assigned or sold your account to them for collection. Receiving their call does not confirm you owe the debt or that the amount is accurate. Request written debt validation before acknowledging or paying anything.
Is United Collection Bureau legit or a scam
UCB is a real, licensed debt collection agency based in Toledo, Ohio. Being licensed does not mean every collection tactic they use is legal. According to BBB records, consumers have filed more than 41 complaints alleging harassment and disclosure failures.
Can UCB report to the credit bureaus
Yes, UCB can report unpaid accounts to Equifax, Experian, and TransUnion, but that reporting must comply with the FCRA. If the entry contains an inaccurate balance or wrong account status, dispute it in writing. The bureau must investigate and respond within 30 days.
Can UCB garnish your wages
No, not without first suing you and winning a court judgment. Any UCB representative who threatens immediate wage garnishment is allegedly making a false statement that violates 15 U.S.C. 1692e(4). That threat alone may constitute a standalone FDCPA violation.
Can you sue UCB even if you owe the debt
Yes. The FDCPA applies to how UCB collects, not to whether the underlying debt is valid. Harassment, false threats, and disclosure failures are actionable regardless of whether you owe the original balance. The statute of limitations for FDCPA claims is one year from the date of the violation.
Your Next Step Before UCB Calls Again
Every UCB call after a documented violation builds your claim. Every unauthorized robocall to your cell adds $500 to $1,500. Every inaccurate credit entry surviving a valid dispute opens an FCRA track. The FDCPA window closes at one year from each violation. Call +1-844-638-1122 today for a free case review. The Wood Firm PLLC works on contingency, and UCB pays attorney fees if federal law was violated.
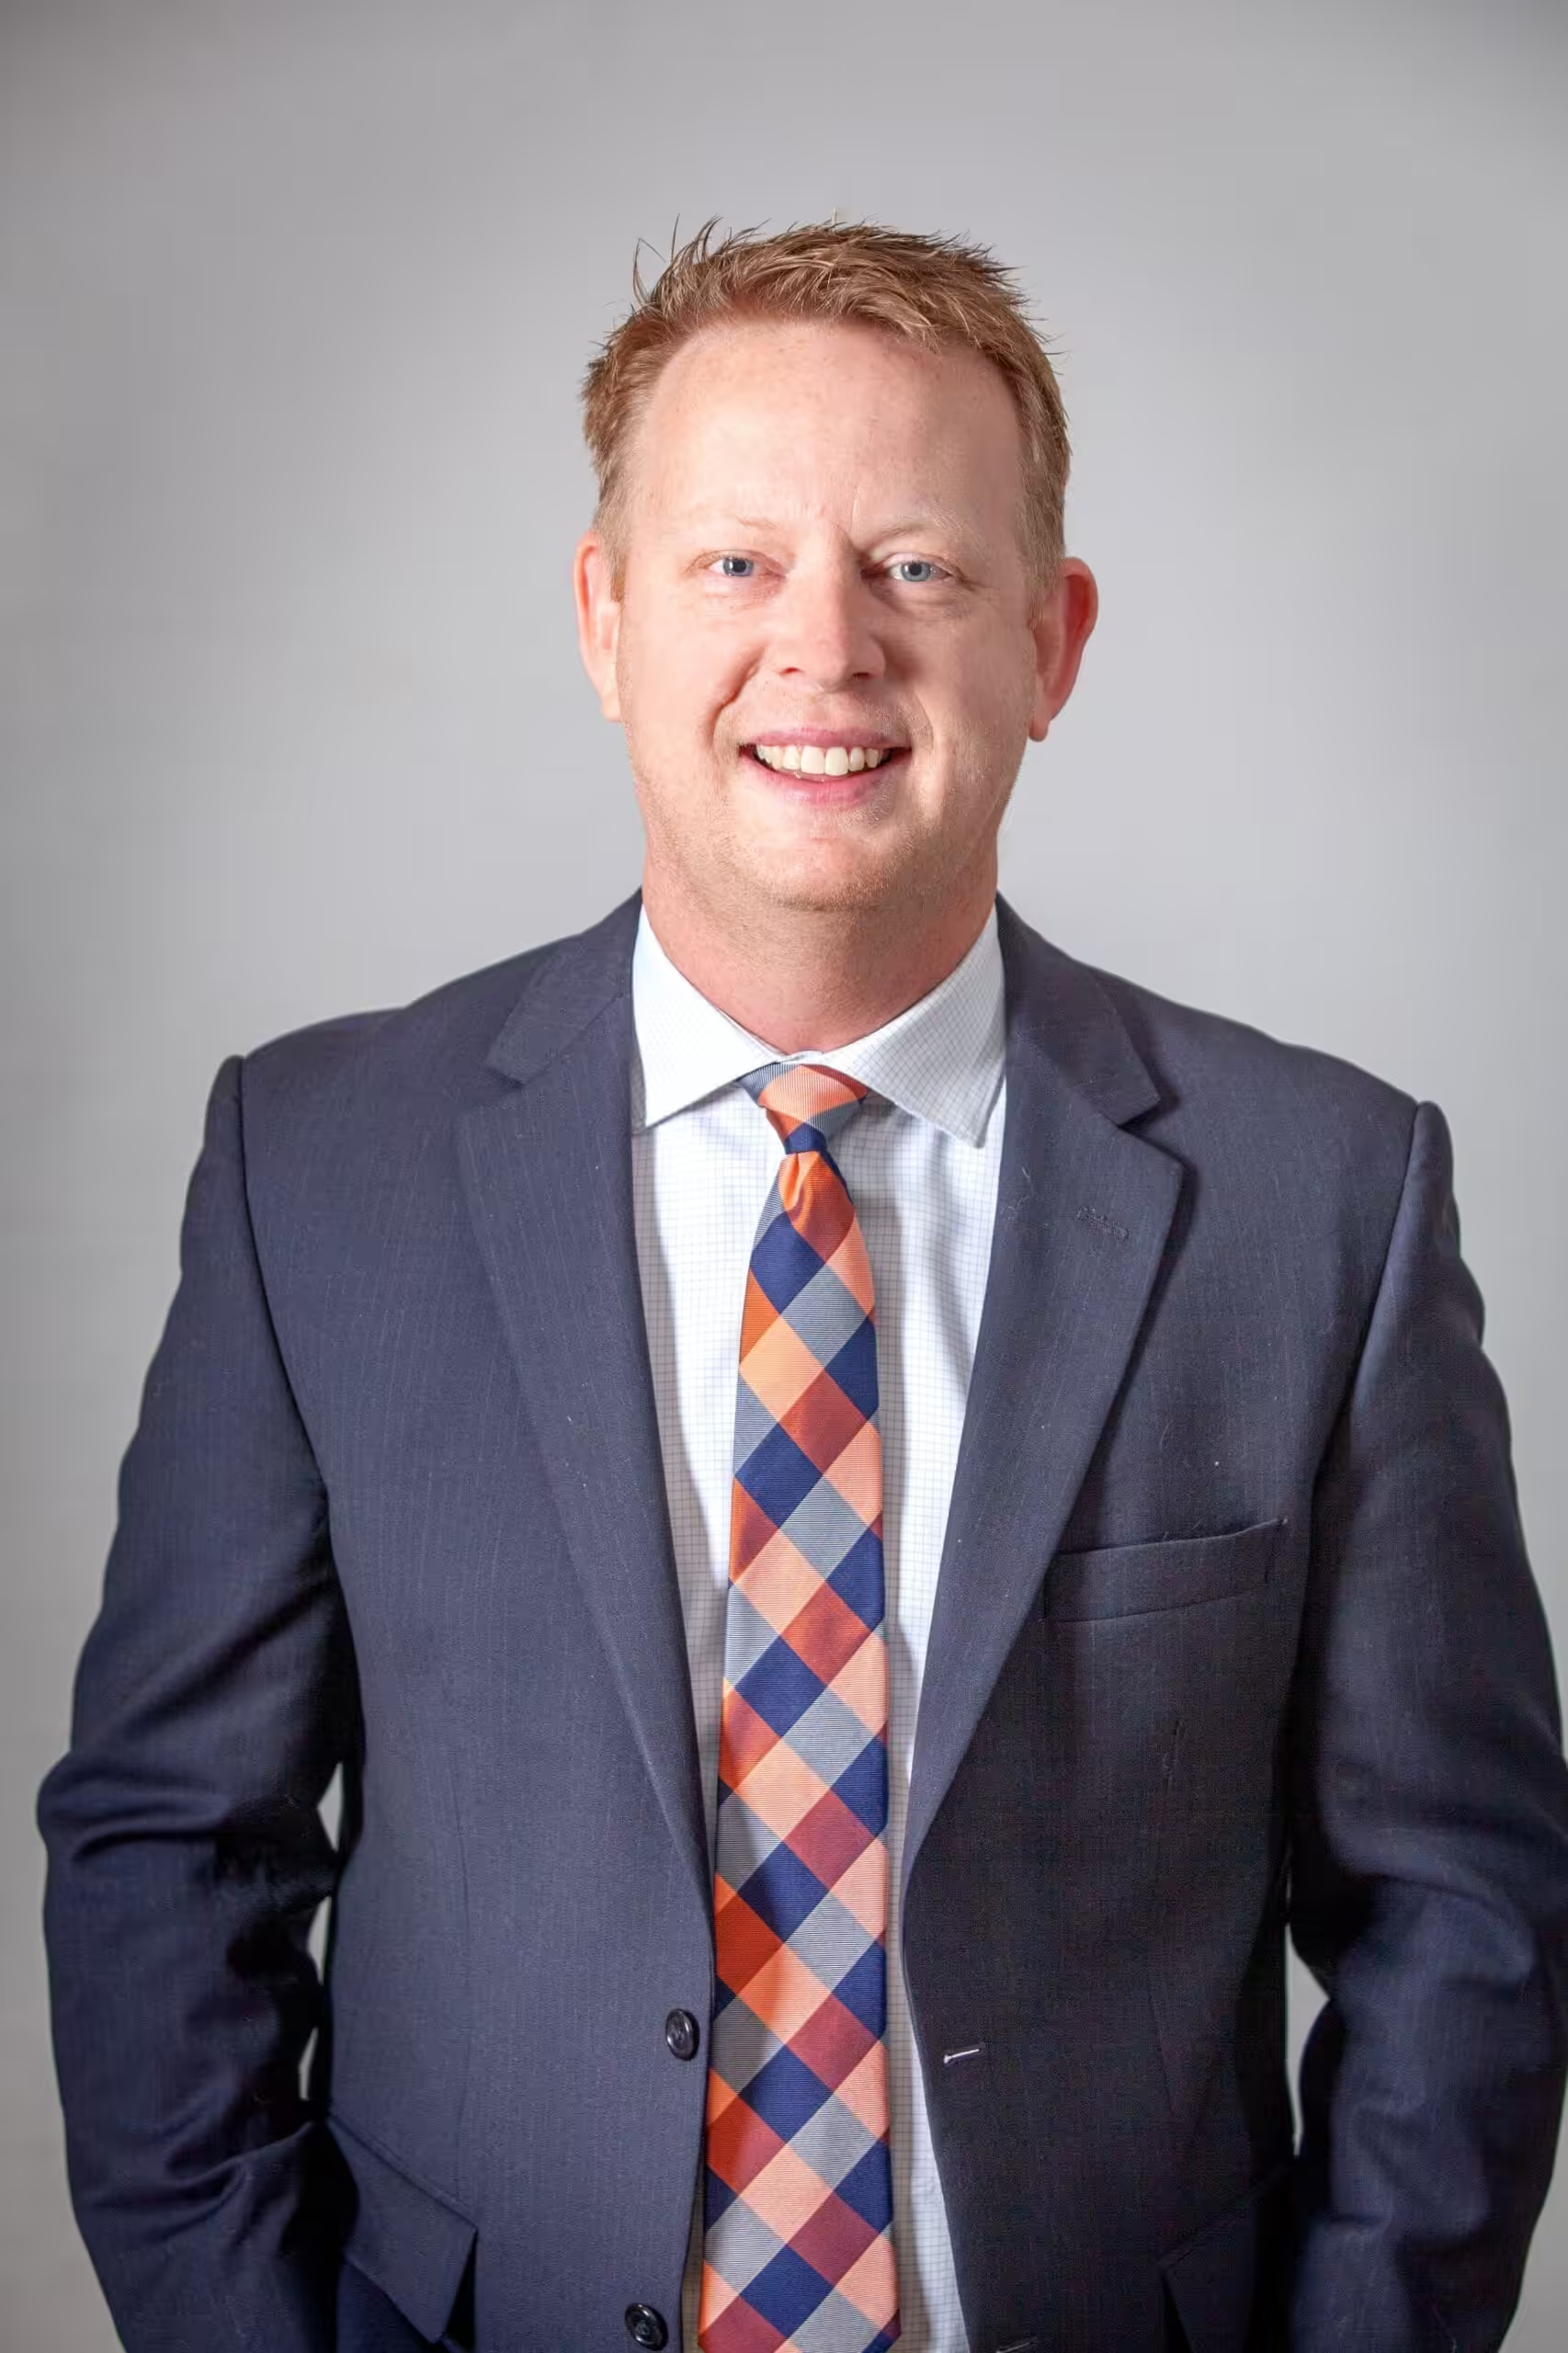
Jeff Wood represents consumers exclusively, never creditors or collectors. He holds federal court admissions across 9 districts, including all courts of AR, CO, NM, and TX. He practices from Little Rock, AR.