Every consumer in the United States holds eight specific, legally enforceable rights. A company that ignores them is not just being difficult. It may be violating federal law, and you may be entitled to compensation.
Key Takeaways
- Consumers in the US hold eight fundamental rights, first outlined in President Kennedy’s 1962 Consumer Bill of Rights.
- The FTC enforces over 70 federal consumer protection laws, with the FDCPA, FCRA, and TCPA covering most everyday violations.
- FDCPA violations carry up to $1,000 in statutory damages; TCPA violations carry $500 to $1,500 per illegal call.
- You generally have one year or less to sue over a specific violation, so documentation matters early.
- Many consumer protection laws require the violating company to pay your attorney fees if you win.
- The Wood Firm PLLC handles these cases on contingency, so you pay nothing unless we win.
Free Case Review: +1-844-638-1122
What Are the 8 Consumer Rights Every American Has?
Every American has eight consumer rights rooted in the 1962 Consumer Bill of Rights. President Kennedy established the original framework, and later laws expanded it to cover data privacy and digital payments.
1. Right to Safety
You have the right to protection from products and services that endanger your health or life. This covers everything from food safety standards to product recall requirements.
2. Right to Be Informed
You have the right to truthful, complete information about a product or service before you buy it. Hidden fees and misleading claims violate this right.
3. Right to Choose
You have the right to select from competing products at fair, competitive prices. Monopolistic or deceptive practices that limit real choice violate this right.
4. Right to Be Heard
You have the right to voice complaints to businesses and government agencies and receive a timely response. This right gives consumers a seat at the table when policy is made.
5. Right to Redress
You have the right to legal recourse when a company violates your rights. That includes filing complaints, suing for damages, and receiving compensation.
6. Right to Consumer Education
You have the right to access information and resources that help you make informed decisions in the marketplace. This right underpins everything else on this page.
7. Right to a Healthy Environment
You have the right to protection from business practices and products that cause unnecessary environmental harm. Regulatory agencies enforce this right through environmental and safety law.
8. Right to Representation
You have the right to have consumer interests represented in government decision-making. Public comment periods and consumer advocacy groups exist because of this right.
What Federal Laws Protect These Consumer Rights?
The FTC enforces more than 70 federal consumer protection laws. Four of them cover most everyday violations.
- Fair Debt Collection Practices Act (FDCPA): prohibits collectors from harassing, deceiving, or using unfair tactics. Violations carry up to $1,000 in statutory damages plus attorney fees.
- Fair Credit Reporting Act (FCRA): governs how your credit information is collected, shared, and corrected. You can dispute inaccurate entries, and bureaus must investigate.
- Telephone Consumer Protection Act (TCPA): restricts robocalls and autodialed messages without consent. Violations carry $500 to $1,500 per call.
- FTC Act: broadly prohibits unfair or deceptive practices, including false advertising and bait-and-switch tactics.
Which Government Agencies Enforce Consumer Rights?
- Federal Trade Commission (FTC): handles complaints about deceptive advertising, scams, and identity theft, and files enforcement actions.
- Consumer Financial Protection Bureau (CFPB): protects consumers in credit cards, mortgages, student loans, and debt collection specifically.
- State Attorneys General: every state runs a consumer protection division that can investigate and sue companies directly.
- Better Business Bureau (BBB): an independent nonprofit that mediates disputes and publishes complaint records.
How Do You Know If Your Consumer Rights Were Violated?
In our practice, most violations we see fall into four categories. Recognizing the pattern is the first step toward a claim.
- Debt collection harassment: calls before 8 a.m. or after 9 p.m., threats of arrest, contacting your workplace, or discussing your debt with family.
- Deceptive advertising: false product claims, undisclosed fees, bait-and-switch tactics, or fake reviews.
- Unfair business practices: refusing to honor warranties, withholding promised refunds, or unauthorized account charges.
- Privacy violations: selling your data without consent, ignoring opt-out requests, or delayed breach notifications.
What Should You Do If Your Consumer Rights Are Violated?
Step 1: Document Everything
Keep receipts, contracts, emails, screenshots, and call logs with dates and times. This record becomes evidence if you file a complaint or a lawsuit.
Step 2: Contact the Company Directly
Reference specific transactions with dates and amounts. State the resolution you want and set a reasonable deadline. Many disputes resolve here, since companies want to avoid regulatory complaints.
Step 3: File Official Complaints
File with the FTC to flag broader complaint patterns, or the CFPB for financial product issues. Your state Attorney General and the BBB also accept and investigate complaints.
In our experience, complaints filed with two agencies at once move faster than a single filing. We often file both the CFPB and a state complaint the same week we open a case.
Step 4: Contact a Consumer Protection Attorney
Consider legal help if the company refuses to resolve the issue or the harassment continues. Many consumer attorneys, including ours, work on contingency. You can also review the most common FDCPA violations before you call.
What Compensation Can You Recover for a Violation?
- Direct damages: refunds, product replacement, repair costs, and out-of-pocket expenses.
- Statutory damages: up to $1,000 per FDCPA violation, or $500 to $1,500 per TCPA violation, available even without proving actual harm.
- Attorney fees: many consumer laws require the company to pay your legal fees if you win.
- Punitive damages: additional penalties for especially egregious conduct, meant to deter repeat violations.
How Can You Protect Yourself as a Consumer?
Before buying, research the company and compare prices across competitors. Read the full contract, and check for complaints with the BBB and your state Attorney General.
During a transaction, keep copies of every document and get promises in writing. Use a credit card for major purchases, since it carries stronger fraud protection than a debit card.
After buying, save your receipts and monitor your statements for unauthorized charges. Respond promptly to recalls and follow up on warranty claims before they expire.
In our practice, we ask new clients for twelve months of statements before we evaluate a billing dispute. That history often reveals a pattern the client had not noticed.
What Rights Do You Have Against Debt Collectors Specifically?
Debt collection harassment is one of the most common consumer rights violations we see. If a collector is contacting you, these protections apply directly.
- You can demand they stop calling with a written cease-and-desist letter.
- You can request debt validation within 30 days, which pauses collection until they prove the debt is yours.
- Collectors cannot call before 8 a.m. or after 9 p.m., or threaten wage garnishment without a court judgment.
- Collectors cannot threaten lawsuits they have no intention of filing.
In our practice, we compare every collector’s call pattern against these exact rules first. If any rule was broken, you may recover up to $1,000 in statutory damages plus fees. Browse our full list of collection agencies if you want to research a specific caller.
How The Wood Firm PLLC Protects Your Consumer Rights
The Wood Firm PLLC has handled FDCPA, FCRA, and TCPA cases exclusively since 2011. We have never represented a creditor or a collection agency. We hold Of Counsel relationships with attorneys in 14 states.
We work on contingency, so you pay nothing unless we recover money for you. Contact typically stops within 48 hours of our legal notice.
Learn more about how we work for you, why clients choose us, or read the attorney profile. Reach The Wood Firm PLLC at +1-844-638-1122.
Whether a debt collector, a lender, or a retailer crossed the line, you have options. Visit our contact page or call +1-844-638-1122 for a free case review. The Wood Firm PLLC handles these cases on contingency, since they only get paid if we win.
Frequently Asked Questions
What are consumer rights?
Consumer rights are legal protections that ensure fair treatment in the marketplace. They include safety, being informed, choice, being heard, redress, education, a healthy environment, and representation.
What should I do if a company violates my consumer rights?
Document everything, then contact the company directly to request resolution. If that fails, file complaints with the FTC, CFPB, your state Attorney General, or the BBB.
How long do I have to file a consumer complaint?
Time limits vary by violation type and state, and some claims expire in as little as one year. Act quickly, since waiting can forfeit your right to compensation.
Can I sue a company for violating consumer protection laws?
Yes. Many consumer protection laws let you sue directly. Most require the company to pay your fees if you win.
What is the FDCPA?
The Fair Debt Collection Practices Act is the federal law regulating how debt collectors treat consumers. It prohibits harassment and deception, with damages up to $1,000 per violation.
Are online purchases protected by consumer rights?
Yes. The same protections apply online and in-store. That includes accurate descriptions, clear fees, and breach notifications.
What Should You Do Next to Protect Your Consumer Rights?
Start by documenting whatever happened, in writing, with dates. If a debt collector, lender, or retailer crossed a legal line, that record is your foundation.
The Wood Firm PLLC reviews these cases on contingency. Call +1-844-638-1122 for a free case review today.
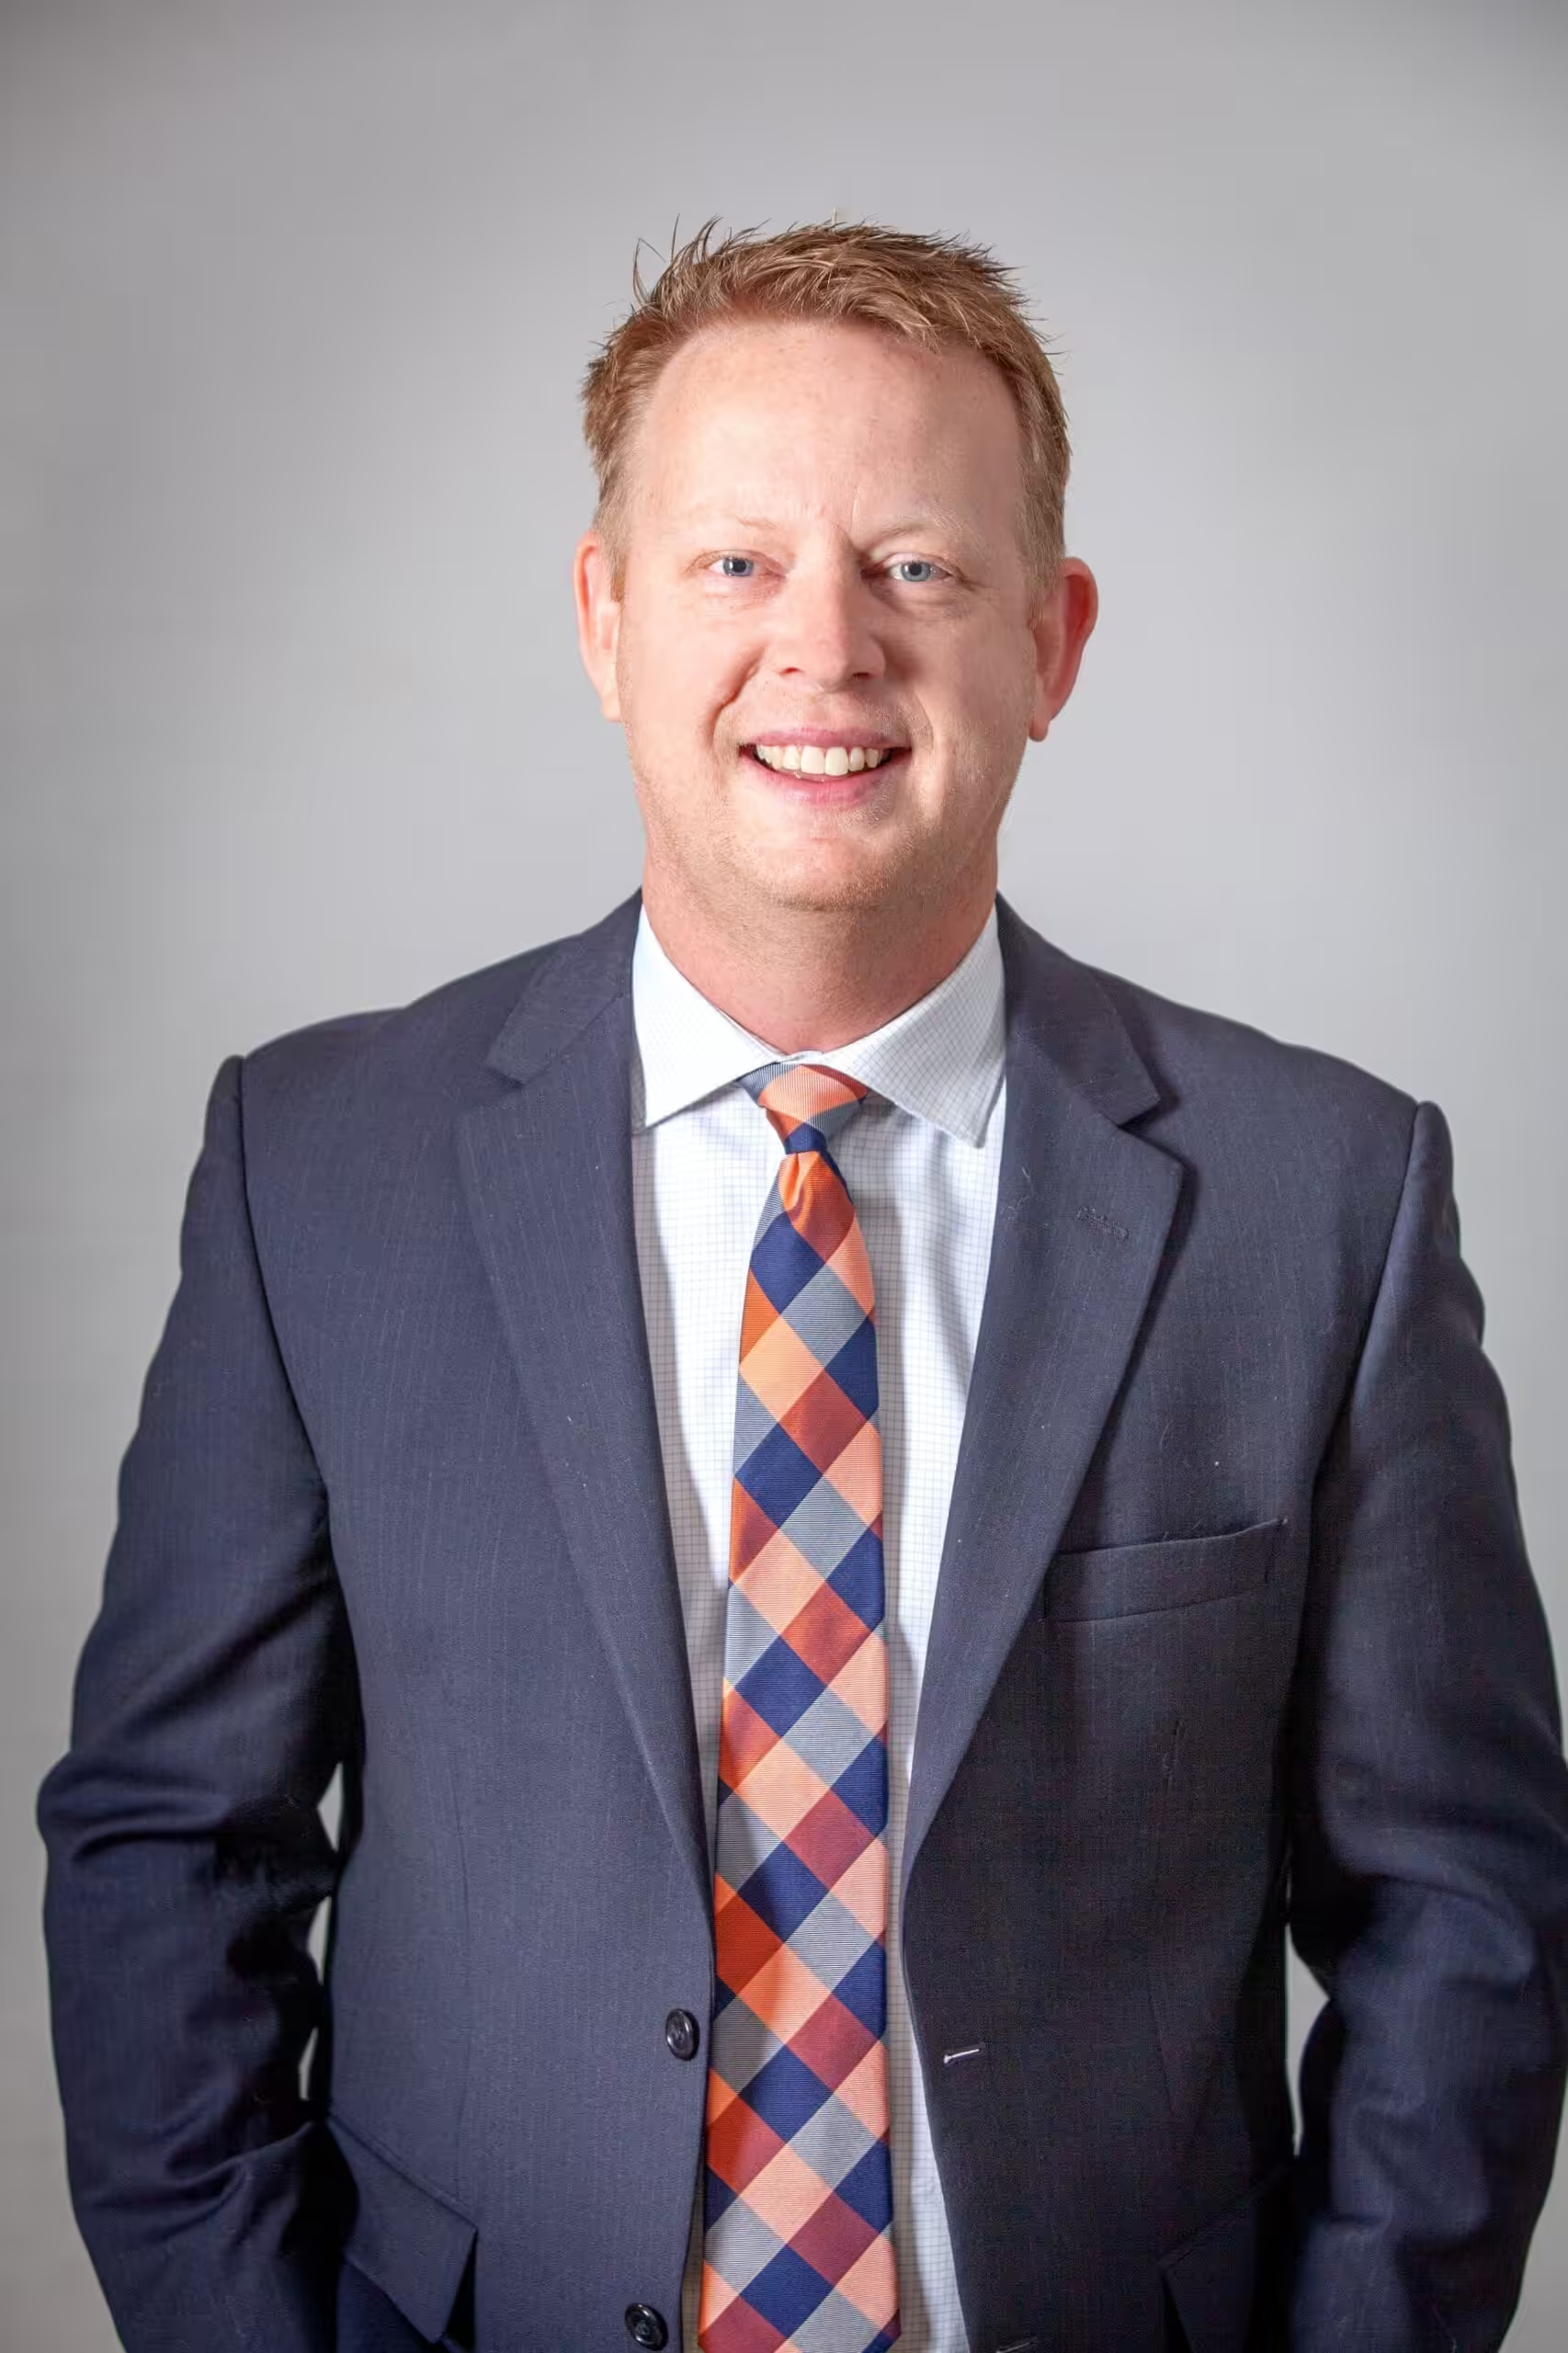
Jeff Wood represents consumers exclusively, never creditors or collectors, with over 15 years of consumer protection experience. He holds federal court admissions across multiple districts and Of Counsel relationships in more than a dozen states. He practices from Little Rock, AR.