A call from Credit Management Company about a bill you don’t recognize is unsettling. Credit Management Company is a Pittsburgh, Pennsylvania debt collector that pursues healthcare, utility, and telecom accounts. According to BBB records, the company has drawn 238 complaints for excessive calling and unauthorized credit reporting.
Reviewed by Jeff Wood, consumer protection attorney. Sourced from BBB, CFPB, and FTC public records. Last updated August 2026.
Key Takeaways
- Credit Management Company (CMC) is a real, licensed debt collector based in Pittsburgh, PA
- They primarily collect healthcare, utility, and telecommunications debts
- According to the BBB, CMC has 238 complaints for excessive calling, unauthorized credit reporting, and misleading debt information
- Federal law protects consumers from abusive collection tactics whether or not the debt is valid
- Not the same entity as Credit Management LP, CMI Group, Harvest Credit Management, or Genesis Credit Management
- The Wood Firm PLLC works on contingency and reviews CMC files at no upfront cost
Free Case Review: +1-844-638-1122
Who Is Credit Management Company?
Credit Management Company operates from Foster Plaza Building 7, 661 Andersen Drive, Suite 110, Pittsburgh, PA 15220. The agency collects unpaid balances for healthcare providers, hospital systems, utility companies, and telecom carriers. Its BBB file lists 238 complaints, most citing excessive calling, misleading debt information, and unauthorized credit reporting.
In our practice, we pull the original creditor placement letter on every CMC file we review, because that document shows exactly when the account was assigned and what balance CMC was authorized to collect. A mismatch between that letter and what CMC later demanded is often the first sign of a validation problem.
Contact information:
- Official phone: (412) 937-0900 | 412-937-0900 | 4129370900
- Also reported: (800) 377-7723 | 800-377-7723 | 8003777723
- Also reported: (713) 231-1866 | 713-231-1866 | 7132311866
- Also reported: (866) 913-4426 | 866-913-4426 | 8669134426
- Also reported: (972) 862-4200 | 972-862-4200 | 9728624200
- Address: Foster Plaza Building 7, 661 Andersen Dr STE 110, Pittsburgh, PA 15220
Why Is Credit Management Company Calling You?
Credit Management Company is calling you because a creditor assigned or sold your account for collection. Their portfolio leans heavily toward healthcare: hospital balances, physician group bills, emergency services, and outpatient care. They also pursue utility arrears and telecom account balances.
Before responding to a medical debt call, verify three things. Confirm the debt is actually yours and not a billing or insurance coordination error. Check that the amount matches your explanation of benefits, and confirm whether the one-year reporting waiting period for medical debt applies.
If you searched “why is Credit Management Company calling me,” this is the Pittsburgh-based collector. Reportedly, they are not affiliated with Credit Management LP, CMI Group, or similarly named firms despite the shared wording.
Is Credit Management Company a Scam?
Credit Management Company is a real, licensed debt collection agency, but licensed does not mean every tactic is legal. According to BBB records and consumer complaints, CMC’s conduct has allegedly included excessive calling, misleading debt information, and unauthorized credit reporting. A call that feels aggressive may reflect documented tactics rather than fraud.
In our experience reviewing CMC complaint patterns, the calls consumers describe as harassment often trace back to autodialed campaigns that continue after a debtor has requested written validation. If calls persisted after you asked for documentation, that timeline matters for a potential claim.
Is Credit Management Company Banned by the FTC?
No. Credit Management Company does not currently appear in FTC enforcement action records available to the public. That does not mean the agency’s practices are unreviewed. Consumers have alleged FDCPA violations to the BBB and the CFPB, and private lawsuits remain a separate avenue for accountability.
If you believe CMC violated federal collection law, a consultation can review your specific calls and letters for FDCPA and FCRA issues, even without an existing FTC action on record.
Credit Management Company on Your Credit Report
If Credit Management Company appears on your Equifax, Experian, or TransUnion report, verify the entry before assuming you owe it. Given the agency’s documented history of unauthorized reporting allegations, entries deserve careful scrutiny.
- Medical debt under $500: should not appear on your report under current rules. Dispute immediately with all three bureaus.
- Medical debt reported within one year of service: dispute with documentation showing the service date, since premature reporting may support both a bureau dispute and an FCRA claim.
- Inaccurate amount: compare against original billing statements and insurance EOBs, then dispute the specific discrepancy in writing.
- Pay-for-delete: negotiate written deletion from all three bureaus before any payment, and get confirmation in writing.
Learn more at the FTC’s debt collection rights resource. Inaccurate reporting may also support a separate Fair Credit Reporting Act claim alongside any FDCPA issue.
How to Stop Calls from Credit Management Company
If you’re receiving calls from any of CMC’s listed numbers, these steps may help.
1. Request Written Debt Validation
Within 30 days of first contact, send a written validation request by certified mail to CMC’s Pittsburgh address. For medical debt, ask for the original provider’s name, an itemized bill, your insurance EOB, and the date of original delinquency. Under the Fair Debt Collection Practices Act, CMC must pause collection activity until it responds adequately.
2. Check Medical Debt Reporting Rules
Federal rules require a one-year waiting period before medical debt reaches credit bureaus, and debts under $500 cannot be reported at all. If CMC reported a medical debt that breaks either rule, that reporting may violate the CFPB’s debt collection rules and support an immediate dispute.
In our practice, we compare the date CMC reported an account against the original service date on every medical debt file, because that single comparison often reveals a reporting violation the client didn’t know existed.
3. Send a Cease-and-Desist Letter
If calls continue after a validation request, a written cease-and-desist by certified mail may help. CMC must then stop contact except to confirm cessation or notify you of legal action. Keep your mailing receipt as proof of delivery.
4. Talk to an Attorney
Once CMC learns you have legal representation, contact should route through your attorney instead of you directly.
How The Wood Firm PLLC Helps Stop Credit Management Company Debt Harassment
CMC’s complaint record points to a few recurring categories: excessive calling, misleading debt information, and unauthorized credit reporting. For healthcare accounts specifically, the medical debt reporting rules add legal angles beyond the FDCPA. We review the placement letter, the call log, and the credit report entry together to see where the account’s documentation breaks down.
The Wood Firm PLLC has handled FDCPA, FCRA, and TCPA cases exclusively since 2010, representing consumers only, never creditors or collectors. We work on contingency, so a review costs nothing upfront and CMC pays our fees if we win. Call +1-844-638-1122.
Whether you owe the debt or not, a review can identify violations worth pursuing. Visit our contact page or call +1-844-638-1122 for a free case review. The Wood Firm PLLC handles these cases on contingency, so if CMC violated federal law, they pay our fees, not you.
Common Questions About Credit Management Company
Is Credit Management Company legitimate or a scam?
Legitimate. CMC is a real, operating Pittsburgh-based debt collector, not a scam. Its 238 BBB complaints for harassment, deceptive practices, and unauthorized reporting document a compliance record worth taking seriously.
Who does Credit Management Company collect for?
CMC primarily collects for healthcare providers, hospital systems, utility companies, and telecom carriers. If they’re calling, the account is most likely a medical bill, utility arrearage, or telecom balance.
Is Credit Management Company the same as Credit Management LP or CMI Group?
No. Credit Management Company in Pittsburgh, PA is a separate entity from Credit Management LP, CMI Group, and other similarly named firms. Request written validation confirming the exact legal entity name before any payment discussion.
CMC appeared on my credit report for a medical debt. Can I dispute it?
Yes, and you may have strong grounds. Medical debts under $500 cannot be reported, and reporting requires a one-year wait after service. If your entry breaks either rule, dispute it with all three bureaus and call +1-844-638-1122.
Can Credit Management Company garnish my wages?
Only after filing a lawsuit, winning a judgment, and obtaining a separate garnishment order. CMC cannot garnish wages from a collection notice alone. A threat of garnishment without a referenced judgment may violate the FDCPA.
Should I pay Credit Management Company before speaking to an attorney?
No. Billing errors and insurance coordination issues are common enough on medical accounts that the claimed balance may not be accurate. A free consultation costs nothing and may reveal violations before you pay anything.
What to Do Next If Credit Management Company Contacts You
Save every call log, voicemail, and letter from Credit Management Company before you respond further. Those records support a validation request and, if warranted, a potential FDCPA or FCRA claim. A contingency review carries no upfront cost either way. Call +1-844-638-1122 to have your file reviewed.
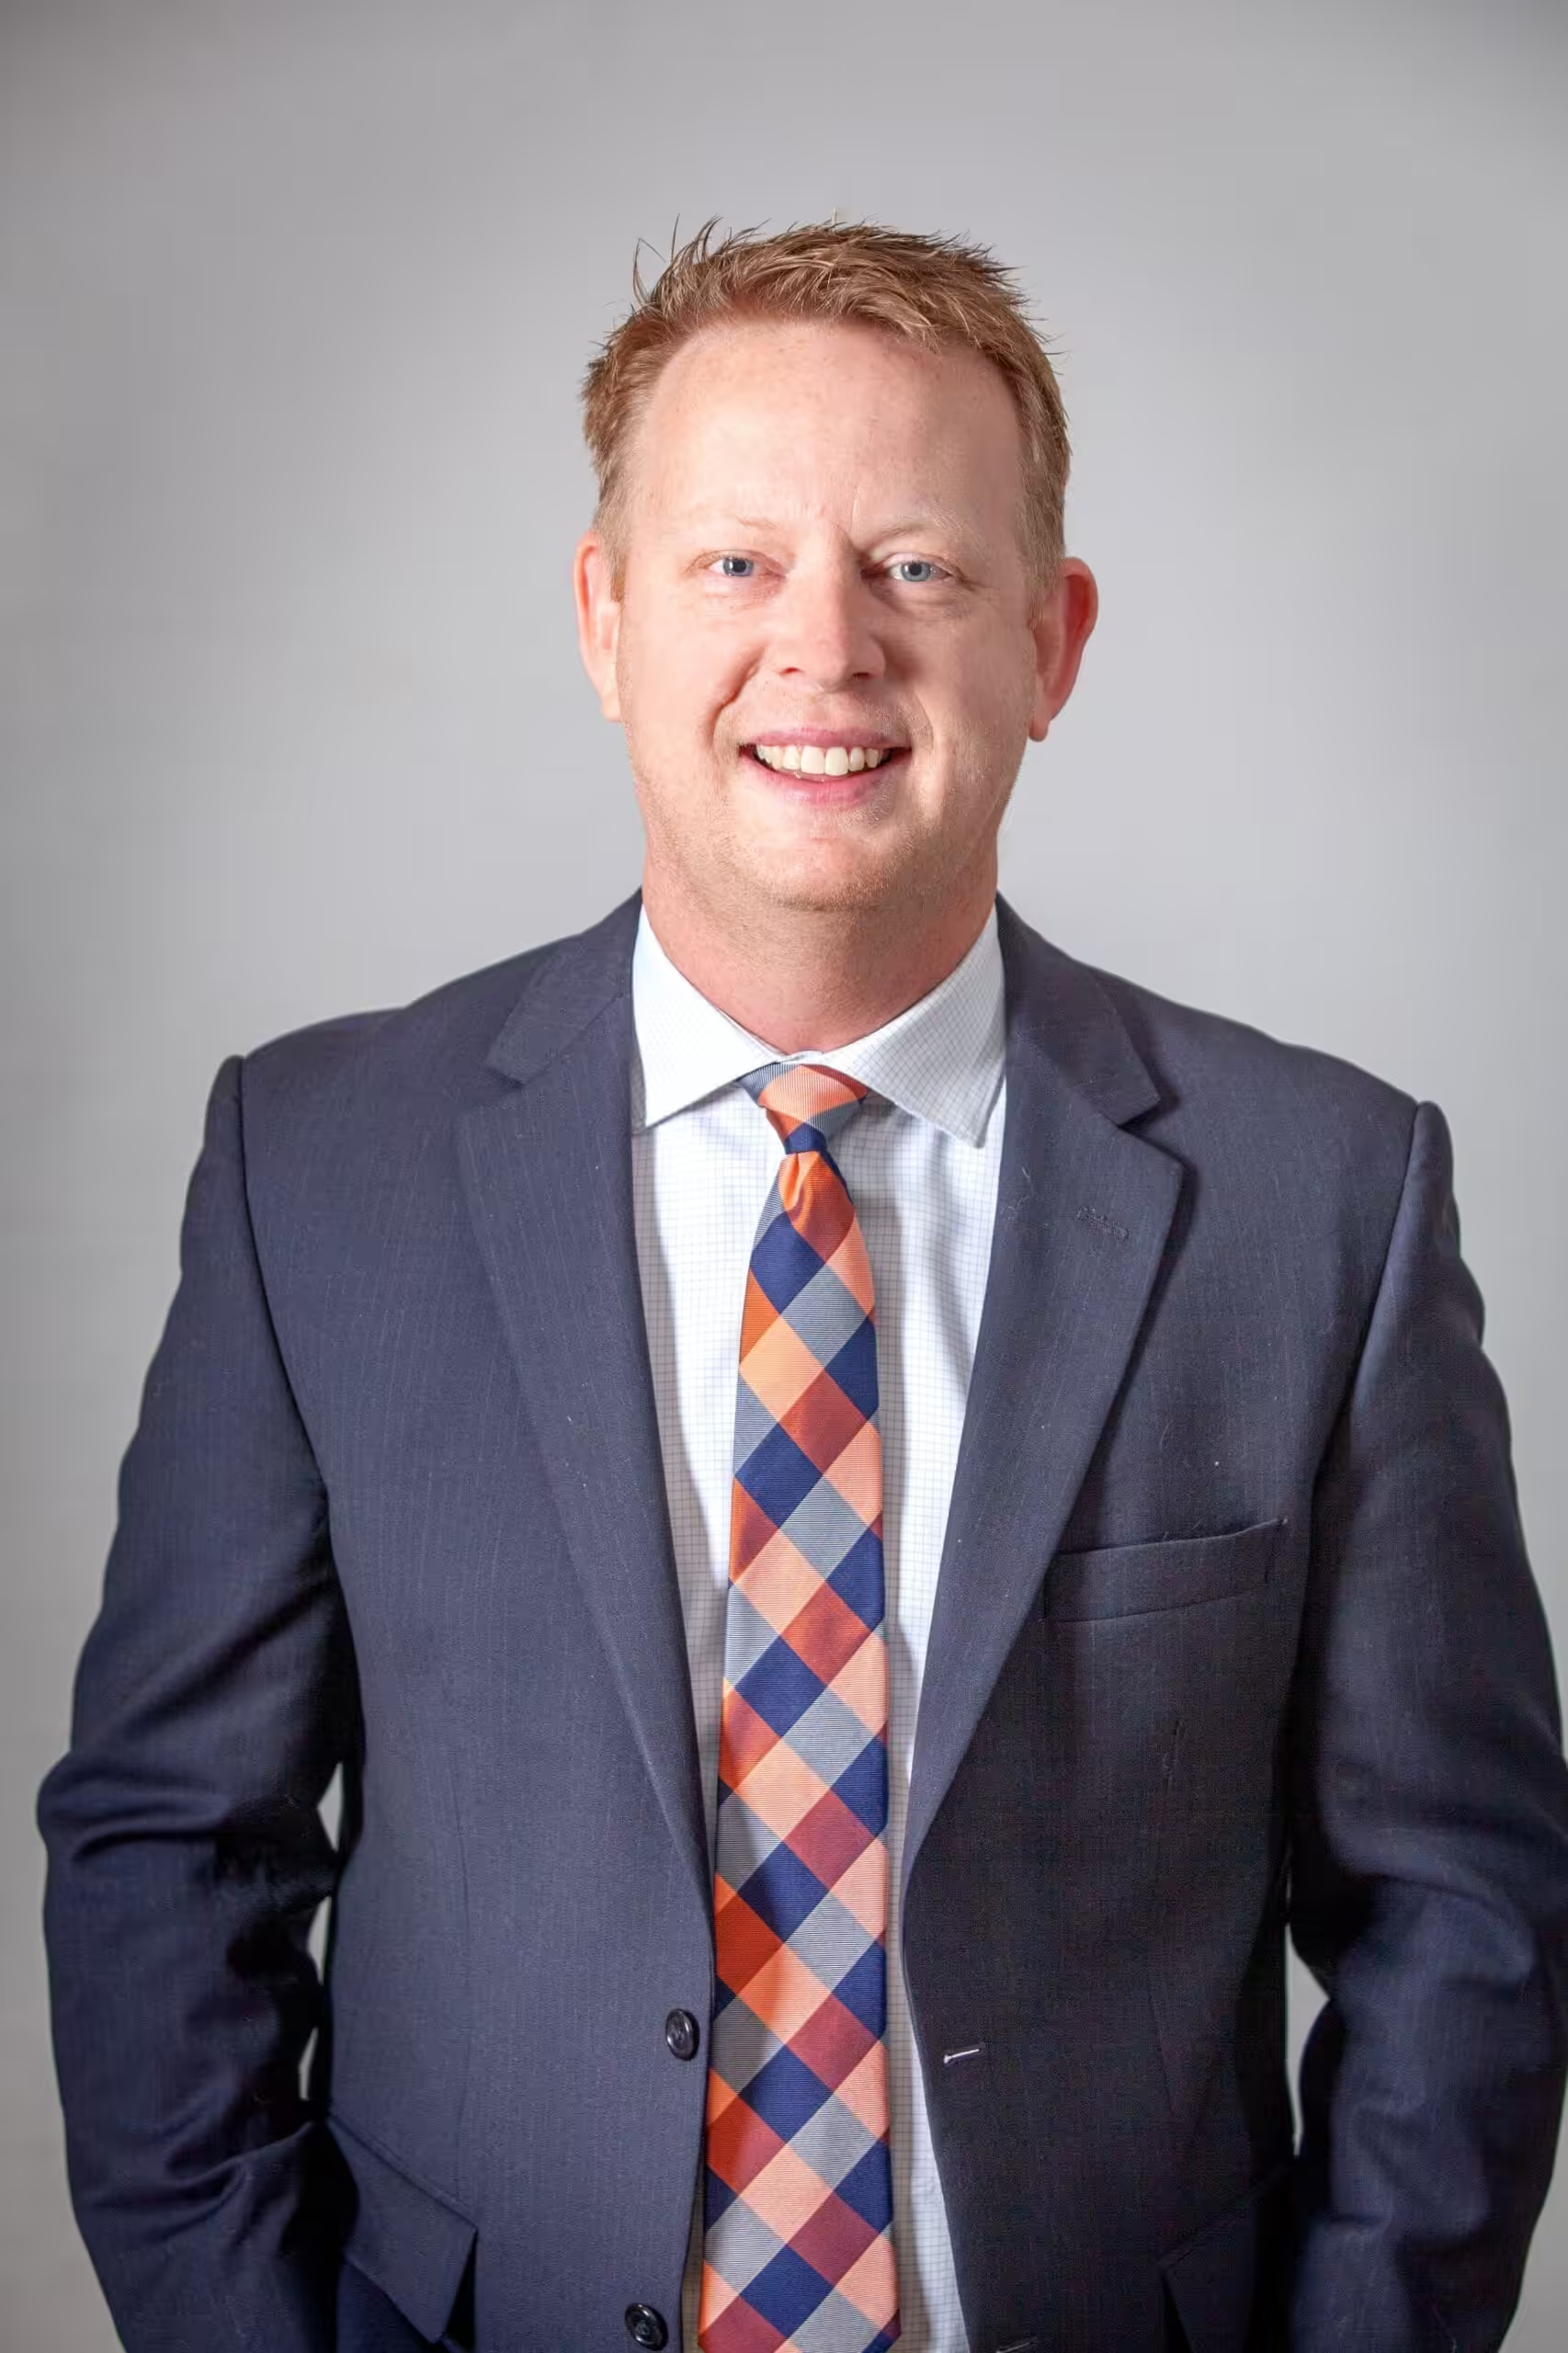
Jeff Wood represents consumers exclusively, never creditors or collectors. He holds federal court admissions across 9 districts, including all courts of AR, CO, NM, and TX. He practices from Little Rock, AR.